Regeneron Pharmaceuticals Inc. stocks have been trading up by 13.1 percent following highly positive news on its latest drug developments.
What Traders Need To Know
- Regeneron posted an exceptionally strong Q3 2026 with 36% total revenue growth and 70% non-GAAP EPS growth, driven by Dupixent, EYLEA HD, and Libtayo.
- Q3 adjusted EPS hit $20.07 versus $16.42 consensus on revenue of $5.12B versus $4.56B, marking a major beat.
- Shares jumped 7–13% after the report, making REGN a top Nasdaq gainer in a weak tape.
- The Sanofi alliance was extended with $1B upfront and up to $7B in milestones, reinforcing collaboration-driven growth.
- Multiple banks raised price targets and reiterated positive ratings on REGN following and around the Q3 print.
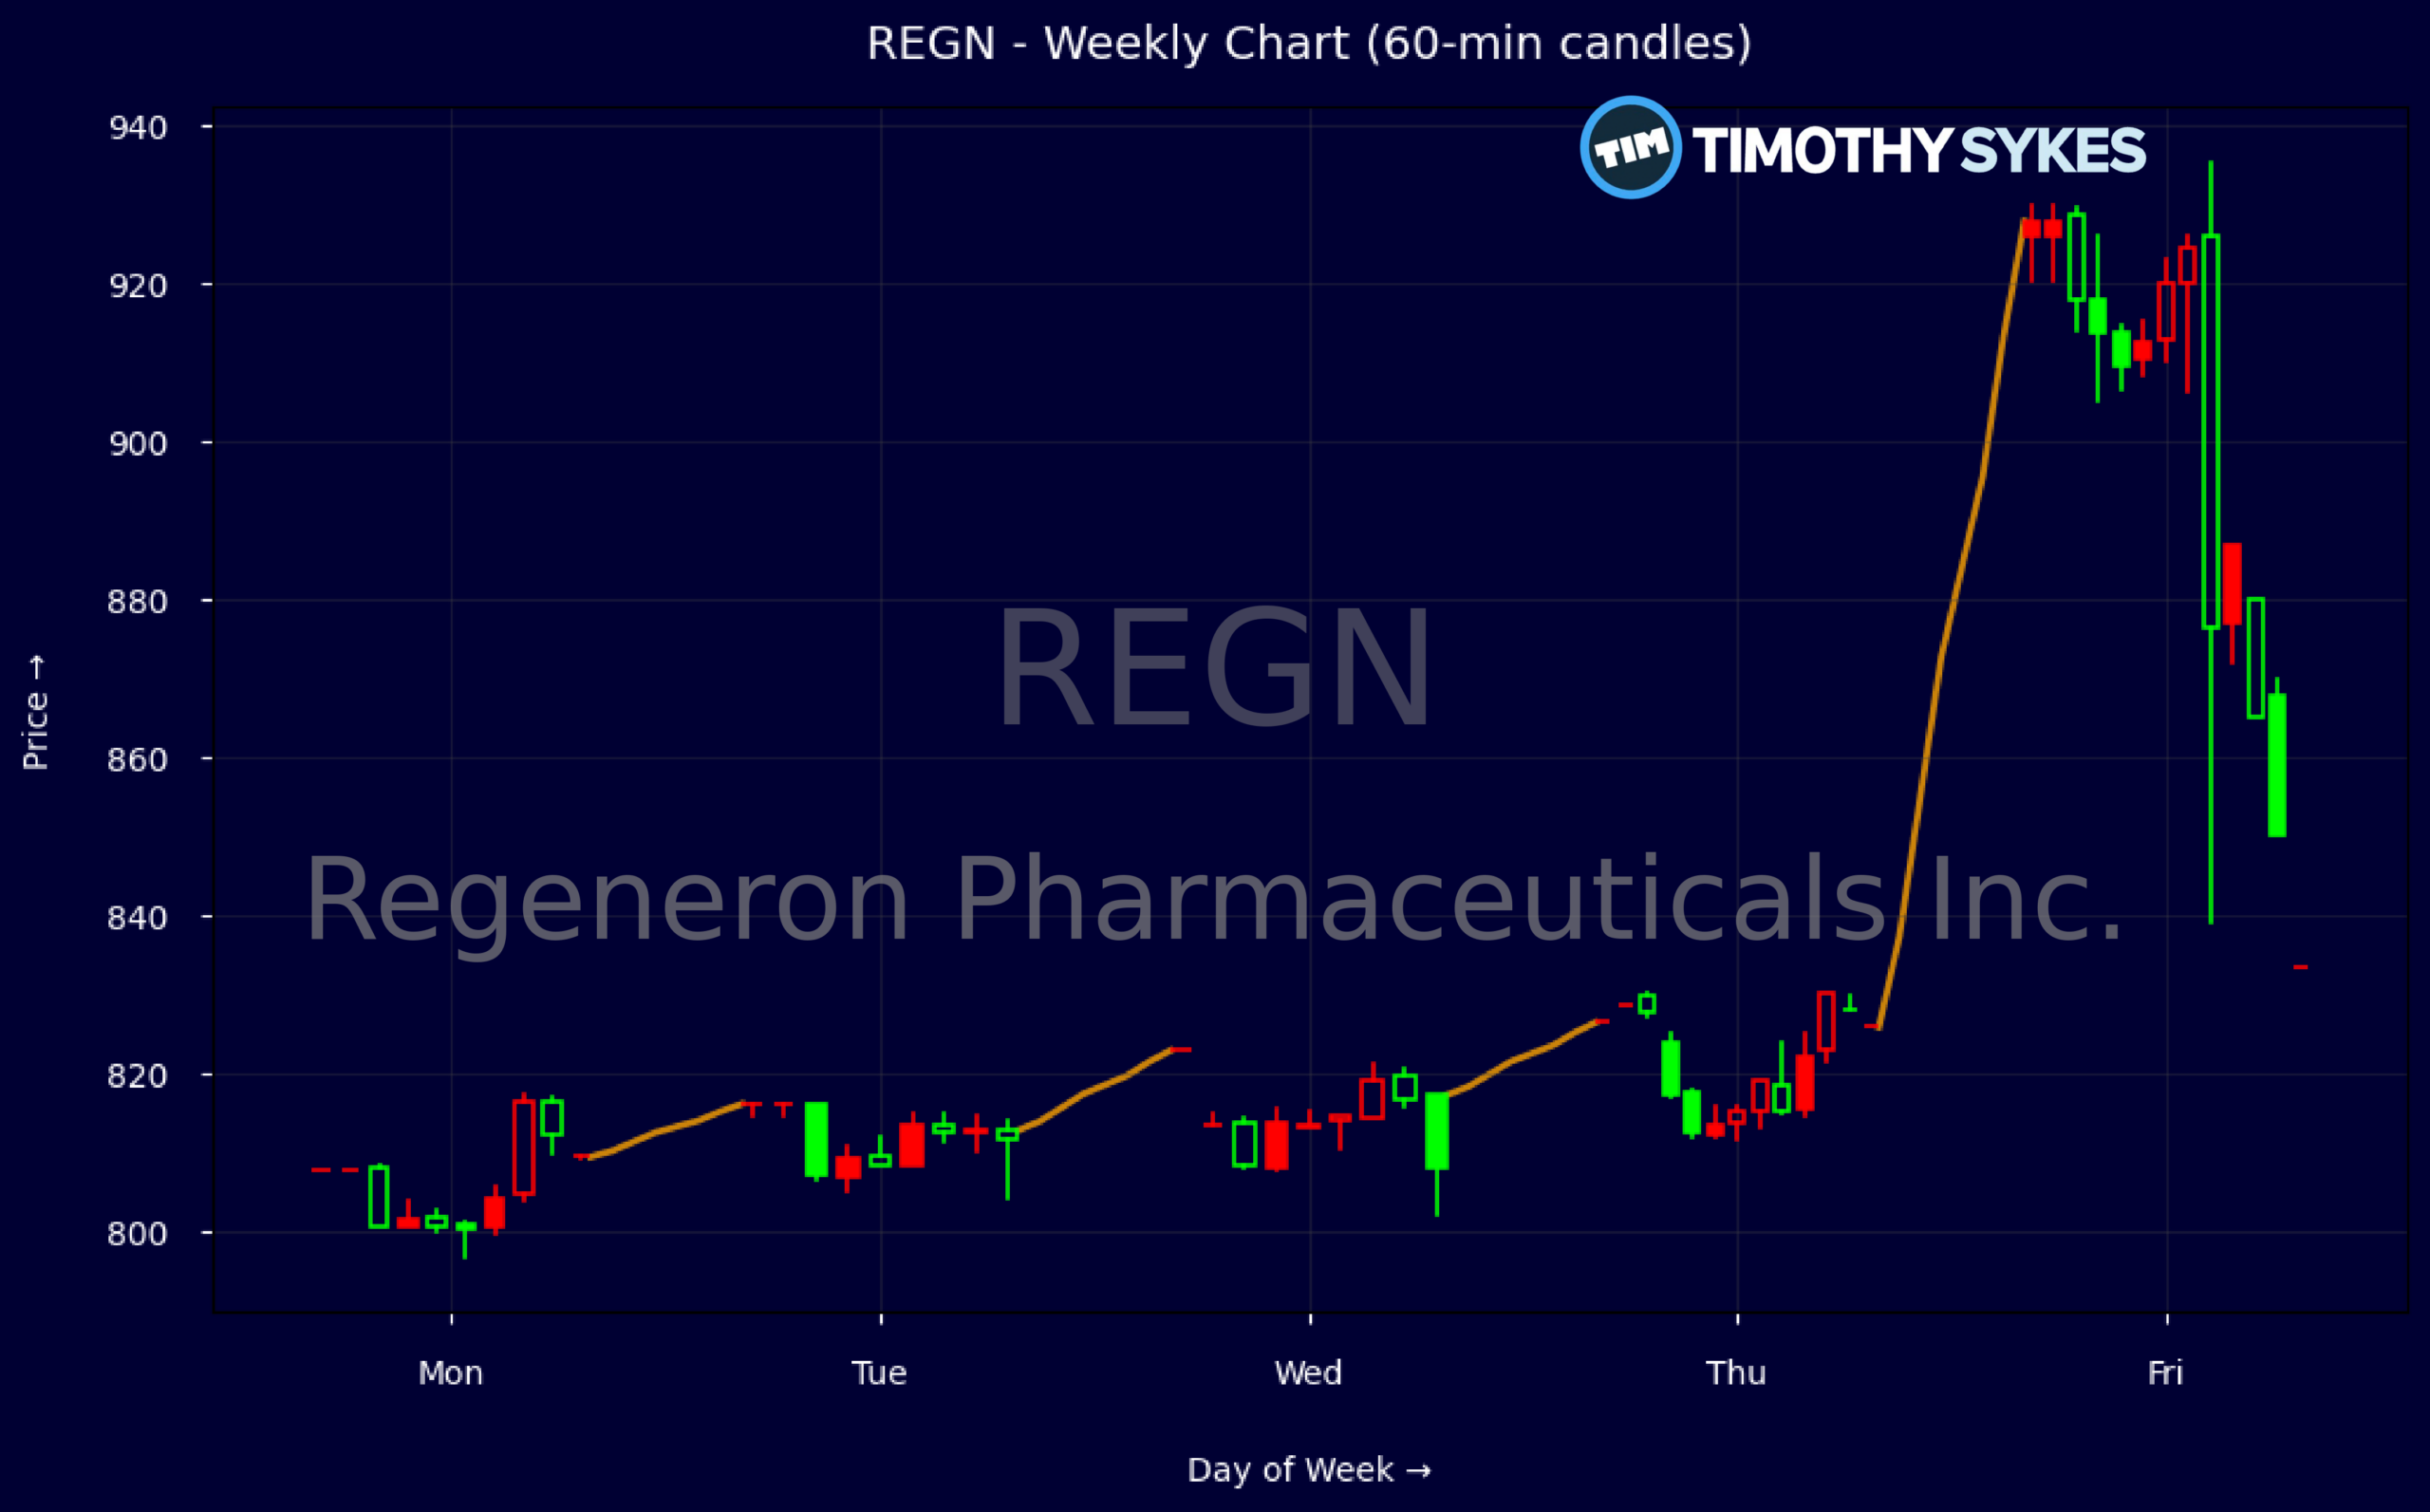
Weekly Update Oct 26 – Oct 30, 2026: On Saturday, October 31, 2026 Regeneron Pharmaceuticals Inc. stock [NASDAQ: REGN] is trending up by 13.1%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Healthcare industry expert:
Analyst sentiment – positive
Regeneron is a top-tier large-cap biotech with big-pharma-like fundamentals and a still-attractive growth profile. Revenue of ~$14.3B growing mid‑single digits historically understates current inflection given 36% Q3 growth. Profitability is elite (EBIT margin 30.6%, gross margin 88.6%, ROE ~18%), underpinned by a durable Dupixent/Eylea/Libtayo triad. Balance sheet strength is exceptional (net cash, D/E 0.09, interest coverage 95.5, current ratio 3.3). Valuation at ~18.5x trailing EPS and ~5x sales is reasonable versus peers given pipeline depth and accelerating cash generation (Q3 FCF $1.48B).
Technically, REGN is in a strong, momentum-driven uptrend. The weekly sequence from ~$808 to $926 reflects a clean breakout week, with the main expansion bar on 10/30 ($920–930 range) confirming institutional buying; intraday 5‑minute tape shows sustained high volume into the close rather than exhaustion. The prior congestion zone near $820 now converts to first key support and a tactical add-on level on pullbacks. Upside, the breakout bar high/close cluster around $930 is immediate resistance; a decisive, volume-backed close above $930 opens a path toward four digits.
Fundamentally and versus Healthcare and Biotech benchmarks, Regeneron screens superior on growth, margins, balance sheet quality, and pipeline breadth. Recent catalysts—blowout Q3, strengthened Sanofi alliance, Libtayo C‑POST survival data, Inmazeb BARDA extension, and new rare-disease approval—justify the wave of target hikes (now largely $980–$1,050) and >70 EPS power in 2026–2027. I expect REGN to outperform XLV and XBI over 12–18 months, with a reasonable upside target of $1,000 and key downside support at $820.
More Breaking News
Quick Financial Overview
Regeneron Pharmaceuticals Inc. delivered a textbook momentum quarter. Q3 2026 revenue reached $5.12B, well ahead of the roughly $4.56B expectation, powering 36% year-over-year growth. Non-GAAP EPS climbed 70% to $20.07, beating the $16.42 consensus by a wide margin. The key engines were surging Dupixent collaboration profits, rapid adoption of EYLEA HD, and strong Libtayo growth, backed by nearly four-year C-POST survival data in high-risk skin cancer.
Under the hood, Regeneron Pharmaceuticals Inc. is running with elite margins. Gross margin sits near 88.6%, while EBIT margin above 30% and profit margin around 28% show strong pricing power and operating discipline. Returns on equity and capital in the mid-teens, combined with very low leverage (total debt-to-equity about 0.09 and interest coverage near 95.5), give the company plenty of balance sheet flexibility. Cash generation is solid: quarterly operating cash flow of about $1.78B and free cash flow near $1.48B support ongoing buybacks, a modest dividend, and stepped-up R&D.
The tape confirmed the fundamentals. On the weekly chart, REGN exploded from the low $800s to close near $926 by the end of the week, with the biggest move landing right after earnings. Intraday, the stock swung between roughly $839 and $935 before settling near the highs, signaling strong dip buying and aggressive chasing. A trailing P/E around 18.5 and price-to-sales near 5 reflect a premium, but not a bubble, especially as multiple banks hiked price targets toward or above $1,000 on the back of the Q3 beat, EYLEA HD mix shift, and the extended Sanofi alliance with $1B upfront and up to $7B in milestones.
Conclusion
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply