
Rocket Companies Inc. stocks have been trading up by 7.64 percent after upbeat mortgage demand and refinancing outlook boosted optimism.
Key Takeaways
- Q3 adjusted EPS of $0.15 for Rocket Companies (RKT) topped consensus estimates of $0.13–$0.14 per share.
- Revenue reached $3.28B versus a $2.58B FactSet consensus, signaling much stronger-than-expected performance.
- Management reported market share gains in purchase and refinance plus the best profitability margin in nearly five years, despite three-year-high mortgage rates.
- Q4 revenue guidance of $2.10B–$2.30B points to solid but lower sequential performance after a standout Q3.
- Street firms including Stephens, Keefe Bruyette, JPMorgan, and RBC adjusted price targets but kept generally positive or neutral ratings, with an average target near $15.42.
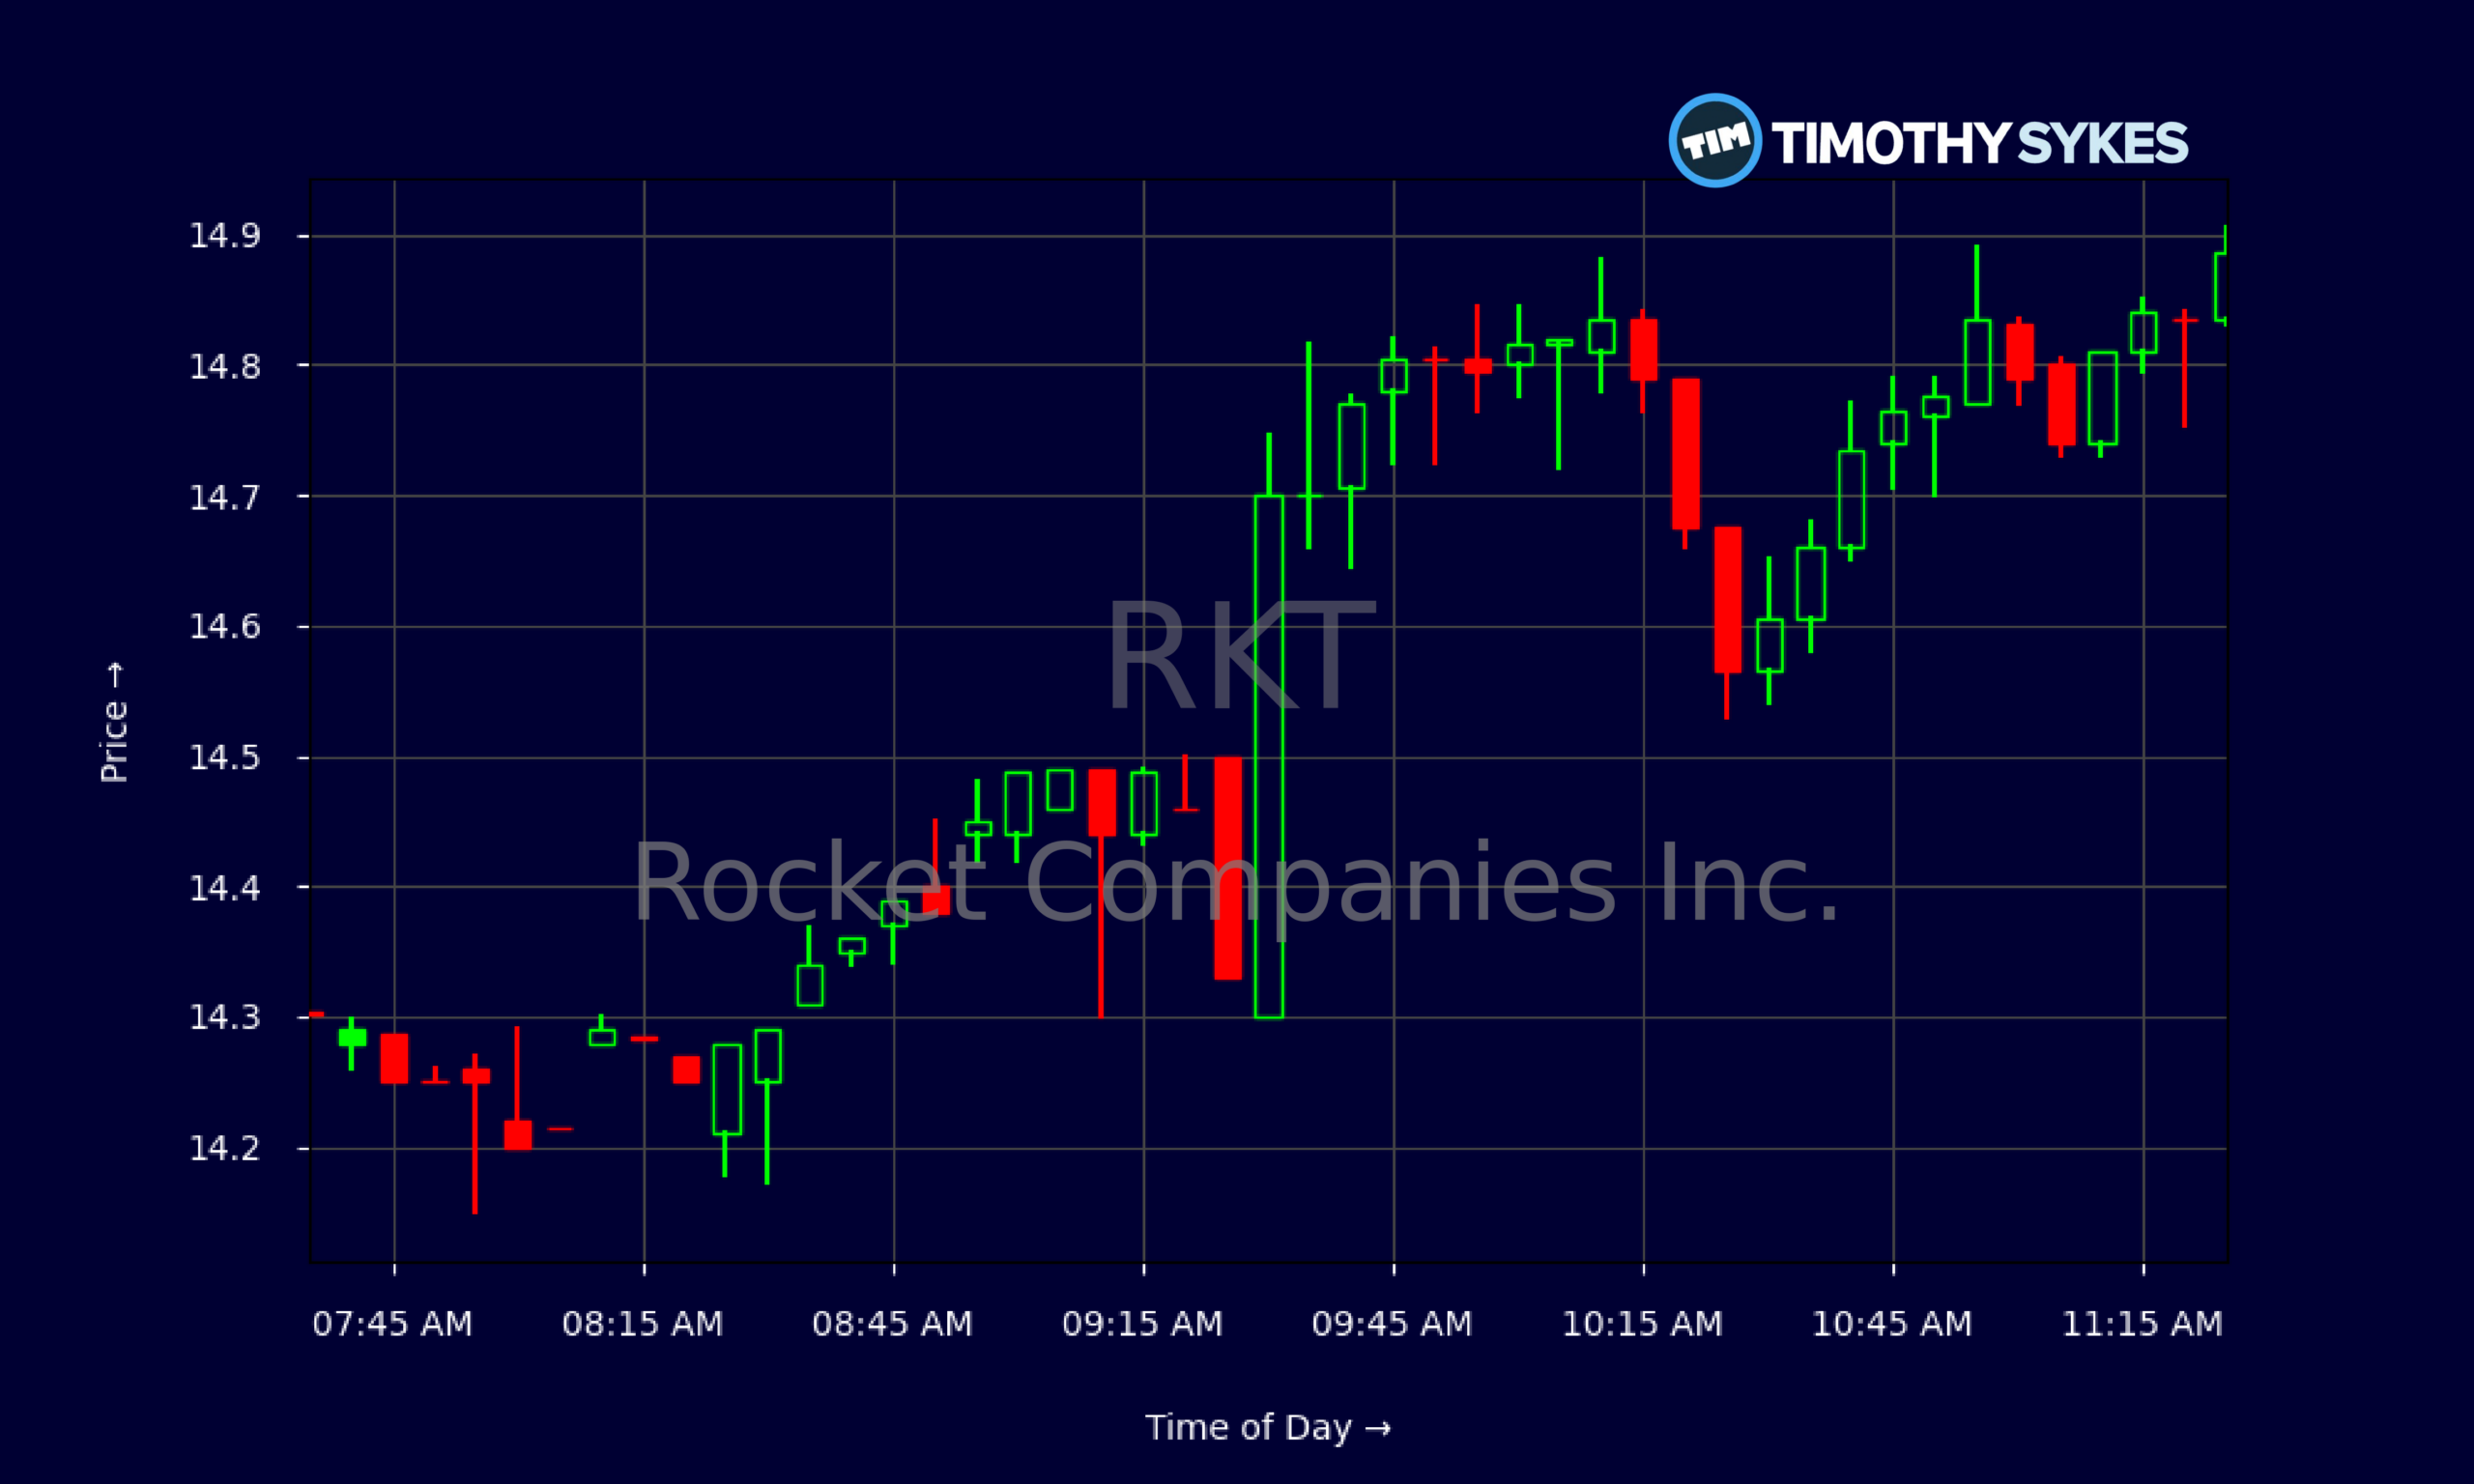
Live Update At 11:32:29 EST: On Wednesday, November 04, 2026 Rocket Companies Inc. stock [NYSE: RKT] is trending up by 7.64%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
RKT has been on a notable run into and after its Q3 earnings. The swing from around $10.50–$11.00 in mid‑October to roughly $14.88 on 2026/11/04 shows how quickly sentiment has shifted in this name. That’s a move of more than 30% in a few weeks, which always gets momentum traders leaning in.
From a fundamentals lens, Rocket Companies printed Q3 total revenue of about $2.10B on the quarter-level financials, while separate Street data points to $3.28B versus a $2.58B consensus. Either way, the message is the same: RKT outpaced expectations. Adjusted EPS came in at $0.15, more than double year over year and ahead of estimates, at a time when many mortgage names are still fighting just to stay profitable.
More Breaking News
The key ratios back up that story. A price-to-sales around 3.63 and price-to-book near 1.38 tell traders the market is willing to pay a premium for Rocket Companies versus a pure book-value mortgage lender, largely because of its tech platform and brand. Leverage is real, with total debt-to-equity at 1.16, but RKT is throwing off serious cash: roughly $1.91B in operating cash flow and $1.86B in free cash flow for the period. For active traders, that combination—rising price, strong cash, and improving margins—often supports follow‑through, but also raises the risk of sharp pullbacks if expectations get too far ahead.
Why Traders Are Watching RKT Now
RKT is sitting at the crossroads of a tough macro backdrop and surprisingly strong execution. Q3 results were the catalyst. Rocket Companies not only beat on earnings with $0.15 adjusted EPS, it did it while mortgage rates hovered around three‑year highs. Management highlighted market share gains in both purchase and refinance and said profitability margins hit their highest level in nearly five years. When a lender grows share and expands margins in a hostile rate environment, traders pay attention.
Yet the tape reminded everyone that headlines are never the whole story. According to the news flow, Rocket Companies’ shares dipped in after‑hours trading on 2026/10/29 despite the big revenue beat to $3.28B versus $2.58B expected. The drag was Q4 guidance: revenue projected in a $2.10B–$2.30B range, meaning management is signaling normalization after a blowout Q3 rather than a straight‑line ramp. For short‑term traders, that shift from “surprise upside” to “steady but slower” often caps immediate upside.
Analysts’ reactions to RKT show the same nuance. Stephens trimmed its target from $16.50 to $16 but kept an Overweight call. Keefe Bruyette also cut from $17 to $16 and stayed Outperform. JPMorgan nudged its target up, from $12.50 to $13 with a Neutral rating, while RBC moved down to $14 and held Sector Perform. Put together, Rocket Companies still carries an overweight‑leaning Street view with a mean target around $15.42—only modestly above recent prices. That suggests traders see upside, but not without volatility and macro risk.
Layer in the housing backdrop and the picture gets more complex. Redfin, now part of RKT’s ecosystem, flagged the first year‑over‑year decline in U.S. median home‑sale prices in more than three years, as high mortgage payments cool demand and inventory rises. For Rocket Companies, that means potential volume pressure, but also an opportunity to grab share as buyers gain a bit more leverage and look for streamlined, tech‑driven platforms. The “Redfin Presents Iconic Homes of America” campaign, running through 2027, fits that strategy: keep customers engaged, build brand gravity, and feed the top of the funnel even when the market is soft.
Conclusion
For active traders, RKT is shaping up as a classic “strong company in a messy sector” story. The stock’s recent push from the low‑$11s to just under $15 tracks directly with the Q3 surprise: revenue well ahead of expectations, adjusted EPS of $0.15, and management talking about multi‑year‑high margins and market share gains. The balance sheet shows real leverage, but the cash‑flow engine—over $1.90B in operating cash flow and hefty free cash flow—gives Rocket Companies room to keep funding tech and marketing while competitors pull back.
At the same time, Rocket Companies isn’t trading in a vacuum. Guidance for Q4 revenue in the $2.10B–$2.30B range signals that management expects a comedown from Q3’s strength, not an endless vertical ramp. Analyst targets around $14–$16, with an average near $15.42, reflect that reality. The Street still leans positive on RKT, but nobody is pretending the rate and housing headwinds vanished overnight.
For short‑term traders, that mix usually means one thing: trade the chart, respect the news, and stay nimble. Momentum in RKT is real, but so is headline risk from rates, housing data, and fresh analyst revisions. As Tim Sykes likes to say, “Traders who last in this game aren’t the ones who nail every trade, they’re the ones who cut losses fast and only press when the odds are stacked in their favor.” That mindset lines up with a broader trading principle that risk management comes first; as millionaire penny stock trader and teacher Tim Sykes, says, “The goal is not to win every trade but to protect your capital and keep moving forward.”. Rocket Companies has stacked a lot in its favor with this earnings print, but the key for traders now is treating every new candle as fresh data, not a guarantee. This article is for educational and research purposes only and is not investment advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:

Leave a reply