Global Payments Inc. jumps as stocks have been trading up by 13.65 percent on optimism over its digital-payments growth.
Key Takeaways
- Oppenheimer upgraded Global Payments to Outperform with a $115 target, pointing to derisked 2026 earnings, 2027 free cash flow acceleration, and Worldpay-driven upside.
- Bank of America reinstated coverage with a Buy and $114 target, highlighting roughly $600M in Worldpay cost and revenue synergies.
- KeyBanc lifted its view to Overweight with a $105 target, citing attractive risk/reward and improving organic growth into FY27.
- Autonomous Research trimmed its target to $95 but kept an Outperform as GPN trades well below a roughly $104 Street mean target.
- Truist cut its target to $86 and stuck with Hold, warning about European softness and higher rates heading into Q3 earnings on 2026/11/05.
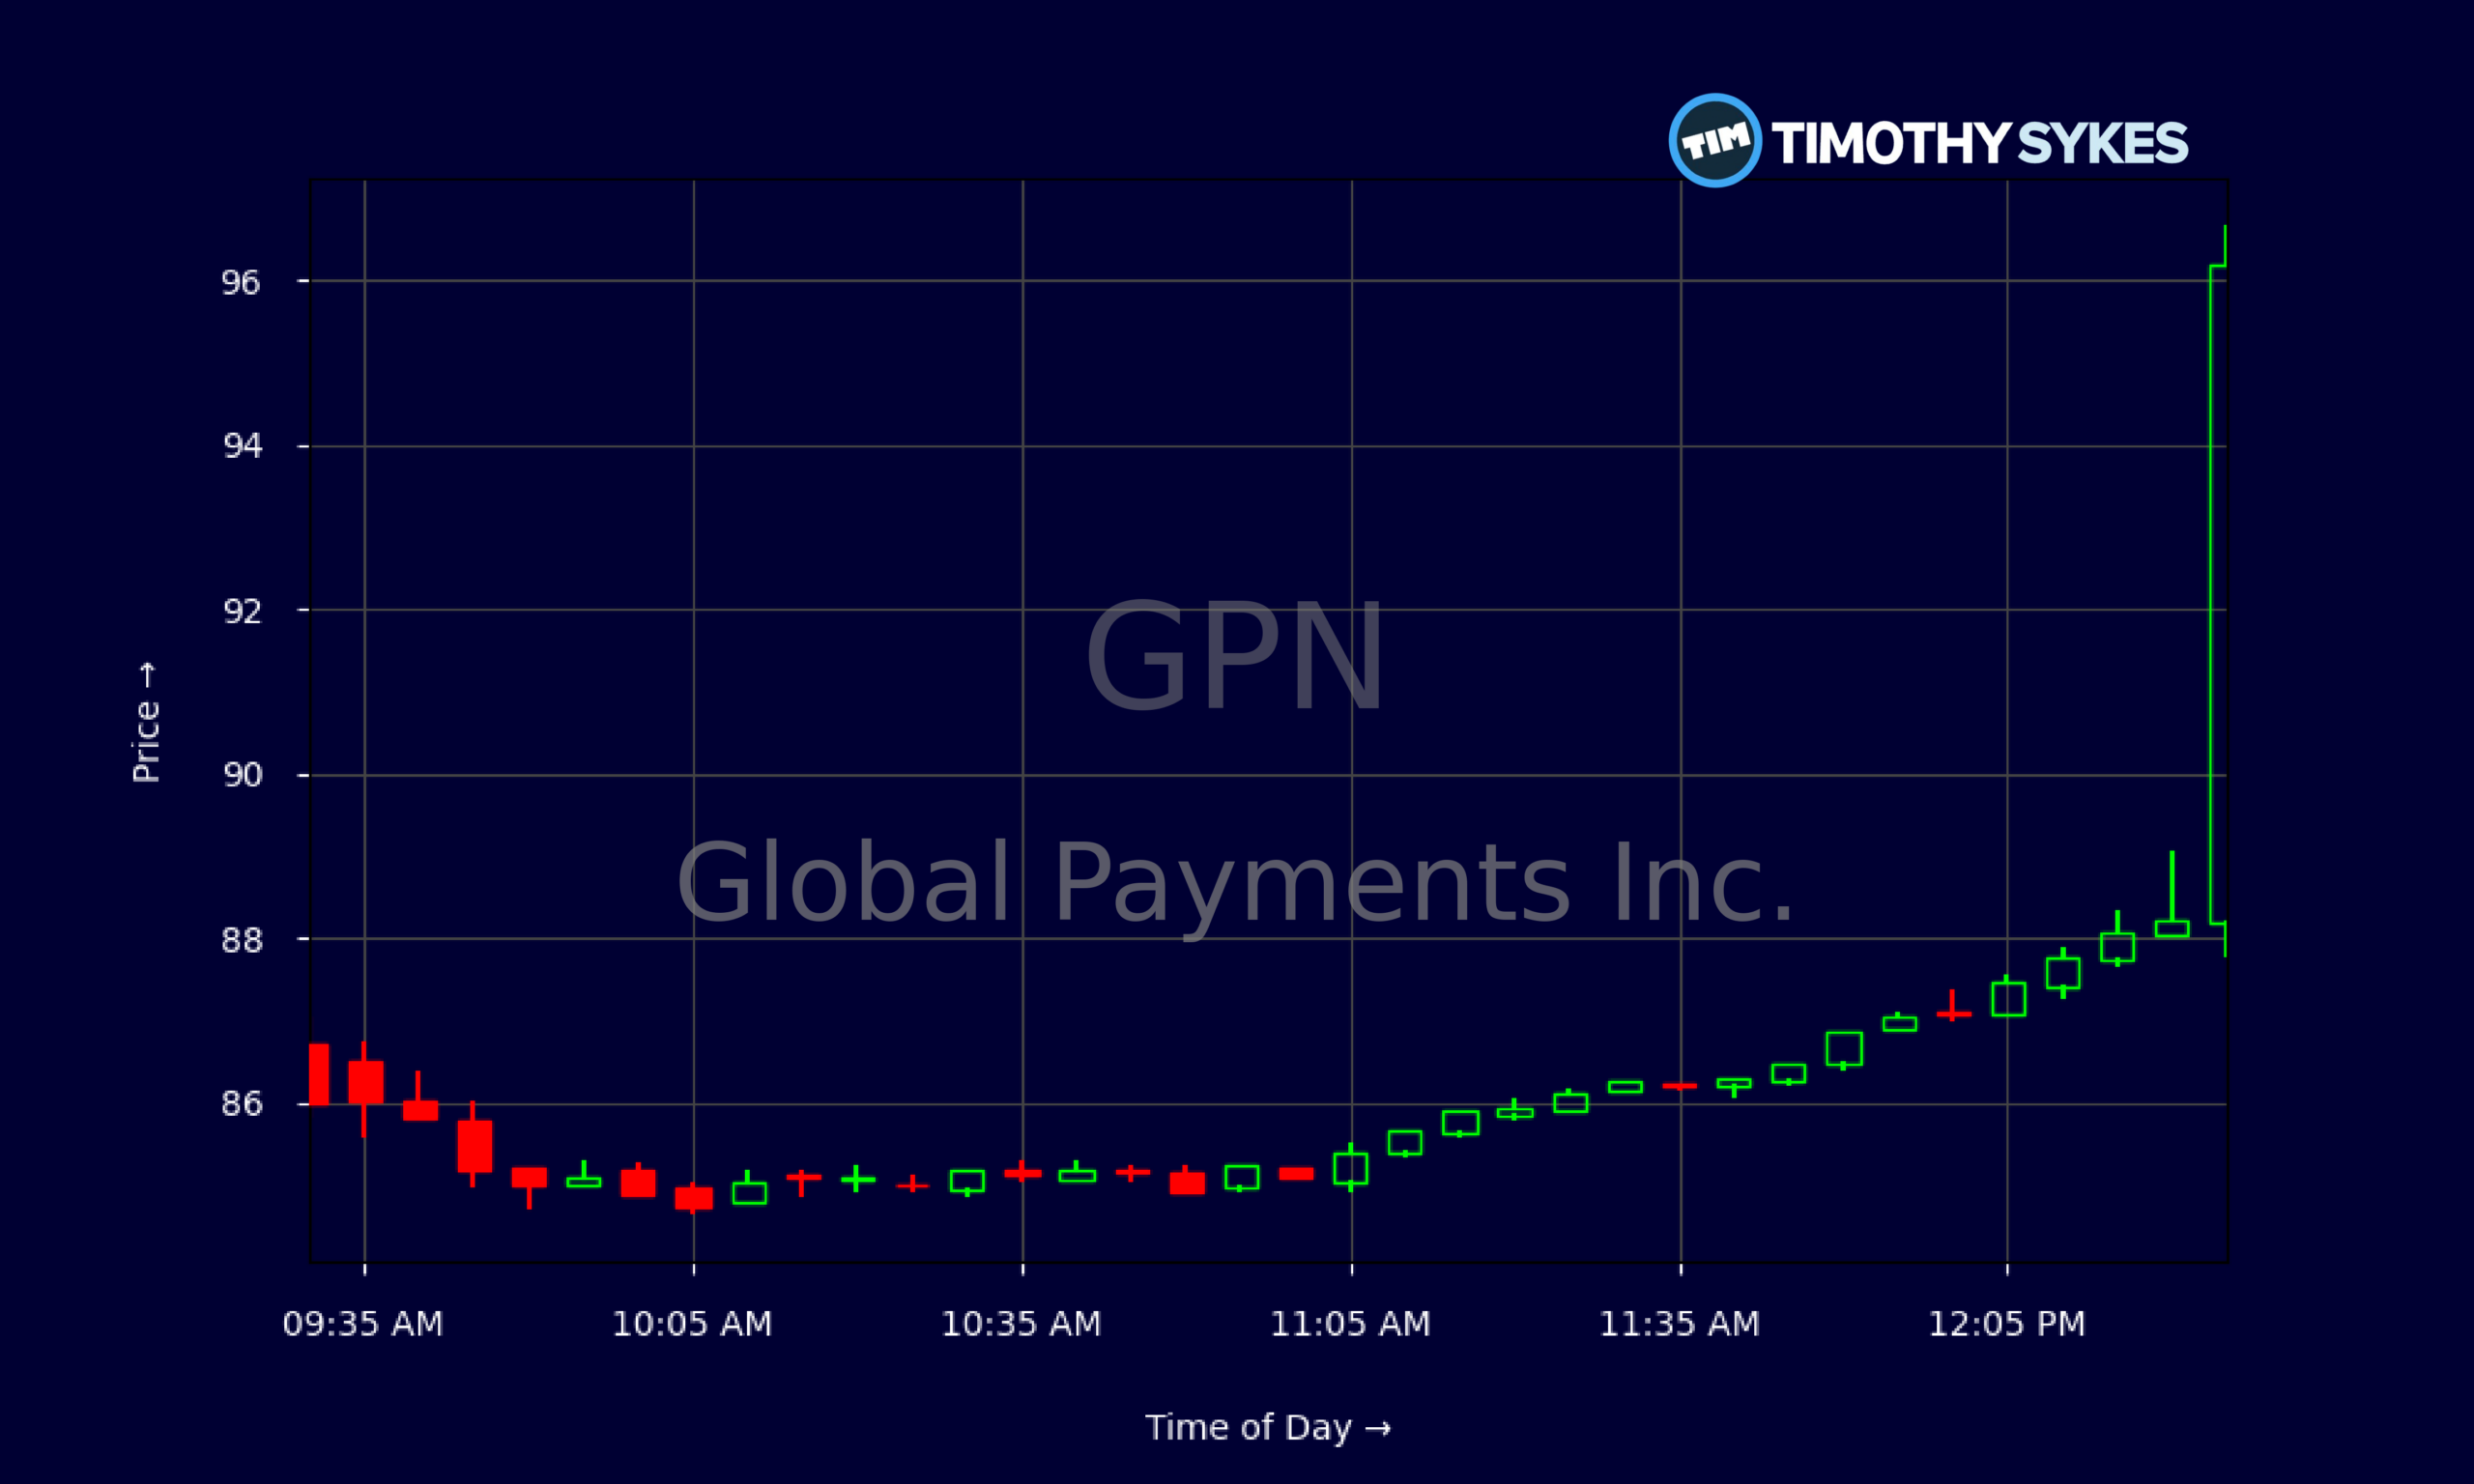
Live Update At 12:32:31 EDT: On Friday, October 30, 2026 Global Payments Inc. stock [NYSE: GPN] is trending up by 13.65%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
GPN has been trading like a coiled spring. Over the last few weeks, Global Payments stock has climbed from around $78–$82 into the high-$90s, with the latest close near $97.60 after a powerful intraday spike. The daily chart shows a steady grind higher, but that last session stands out as a clear momentum surge.
On the 5‑minute chart, GPN spent most of the morning churning between $85 and $87. Then volume kicked in after midday, and the stock ripped from the high‑$80s to above $97 in a straight trend move. For short‑term traders, that’s a classic range‑break and short‑squeeze pattern: tight consolidation, then a vertical push once resistance fails.
More Breaking News
Fundamentals give this move some backbone. Global Payments generated about $7.7B in revenue over the last year with a hefty 93% gross margin and strong EBITDA margin above 30%. Net margins are messy because of one‑time charges and heavy amortization, but cash flow is solid, with roughly $427M in free cash flow last quarter alone and a price‑to‑free‑cash ratio near 12.7. At a share price in the $80s–$90s and book value per share around $87, GPN has been trading near book, while still throwing off cash and a modest dividend around 1.1%. That mix of discounted valuation and cash generation is exactly what many bigger funds and active traders hunt for when sentiment starts to turn.
Why Traders Are Watching GPN Into Earnings
The story around GPN right now is all about a sentiment reset. For months, Global Payments lagged while traders favored flashier fintech names. Now, a wall of analyst calls is forcing the market to re‑price the stock ahead of Q3 results on 2026/11/05.
Oppenheimer fired the first big shot, upgrading Global Payments to Outperform and planting a $115 target on the name. Their thesis is simple but powerful: 2026 earnings risk is coming down, 2027 free cash flow should speed up as one‑time costs fade, and the Worldpay deal has more juice left in it. They’re talking mid‑single‑digit revenue growth, better operating leverage, and extra upside from synergies and capital returns. For swing traders, that sounds like a classic “under‑owned compounder” setup.
Bank of America backed that up by reinstating coverage of GPN with a Buy rating and a $114 target. They leaned hard into Worldpay as well, calling out roughly $600M in combined cost and revenue synergies. That’s real money for a company doing around $7.7B in sales. If Global Payments executes, those synergies can widen margins and support higher free cash flow, which the Street usually rewards with a higher multiple.
KeyBanc joined the bull camp with an upgrade to Overweight and a $105 target, framing current GPN levels as an attractive risk/reward for a 6–12 month re‑rating. They see modest organic growth improvement into FY27 and like the company’s capital return playbook. Meanwhile, Autonomous Research still calls the stock Outperform even after trimming its target slightly to $95, and Goldman Sachs nudged its target up to $98. Across the board, consensus sits around $104–$105 versus a prior trading level near $82, signaling meaningful upside in the models.
The one loud skeptic is Truist. They cut their target to $86 and kept a Hold, warning that European consumer weakness and higher rates make the setup tricky for payments and fintech names into Q3. For traders, that note matters. It’s a reminder that Global Payments still faces macro headwinds even as Wall Street grows more optimistic.
Conclusion
For active traders, GPN is shaping up as a textbook catalyst play. The stock has broken out on heavy volume just as a cluster of big banks — Oppenheimer, Bank of America, KeyBanc, Goldman Sachs, and Autonomous — crowd into the bullish camp with price targets well above recent trading levels. At the same time, the business behind Global Payments is throwing off solid cash flow, trading near book value, and working to unlock large Worldpay synergies over the next couple of years.
But this is not a one‑way bet. Truist’s more cautious stance reminds everyone that macro risk is still on the board, especially in Europe, and that earnings on 2026/11/05 are the real test. If GPN’s Q3 numbers and outlook back up the free‑cash and synergy story, the current breakout can extend. If they disappoint, late chasers risk getting trapped near the highs.
This is exactly the type of setup Tim Sykes talks about when he says, “The market rewards preparation, not prediction.” As millionaire penny stock trader and teacher Tim Sykes, says, “The goal is not to win every trade but to protect your capital and keep moving forward.”. Traders who study the Global Payments chart, understand the Worldpay catalyst, and plan their risk around that earnings date are the ones most likely to stay in control. As always, this analysis is for educational and research purposes only, not advice to trade or not to trade any security — use it as a framework to build your own trading plan around GPN.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply