
DT Midstream Inc. stocks have been trading up by 4.09 percent on optimism over stronger midstream demand and earnings.
What Traders Need To Know
- Jefferies raised its price target on DT Midstream to $150 from $145 and reiterated a Buy rating, pointing to rising utility and data center gas demand that supports follow-on projects and a stronger, more visible growth runway beyond 2030.
- Scotiabank slightly reduced its price target on DT Midstream from $168 to $165 but reaffirmed an Outperform rating, citing a moderation in second-half performance after a strong first half and a flat-to-down earnings revision trend despite elevated commodity prices.
- Barclays trimmed its price target on DT Midstream to $142 from $143 while maintaining an Equal Weight rating, saying it needs more proof that the company can benefit from rising gas and power demand amid strong competition.
- UBS expects DT Midstream’s Q3 EBITDA to decline modestly quarter over quarter due to gathering-system maintenance and seasonal volume softness, but keeps a Buy rating and a $170 price target backed by a solid committed backlog and upcoming project updates despite execution and cost risks.
- The company released its annual Corporate Sustainability Report, stressing ESG progress and long-term natural gas infrastructure demand, and will report Q3 2026 earnings before the market opens on 2026/10/29, followed by a conference call and webcast.
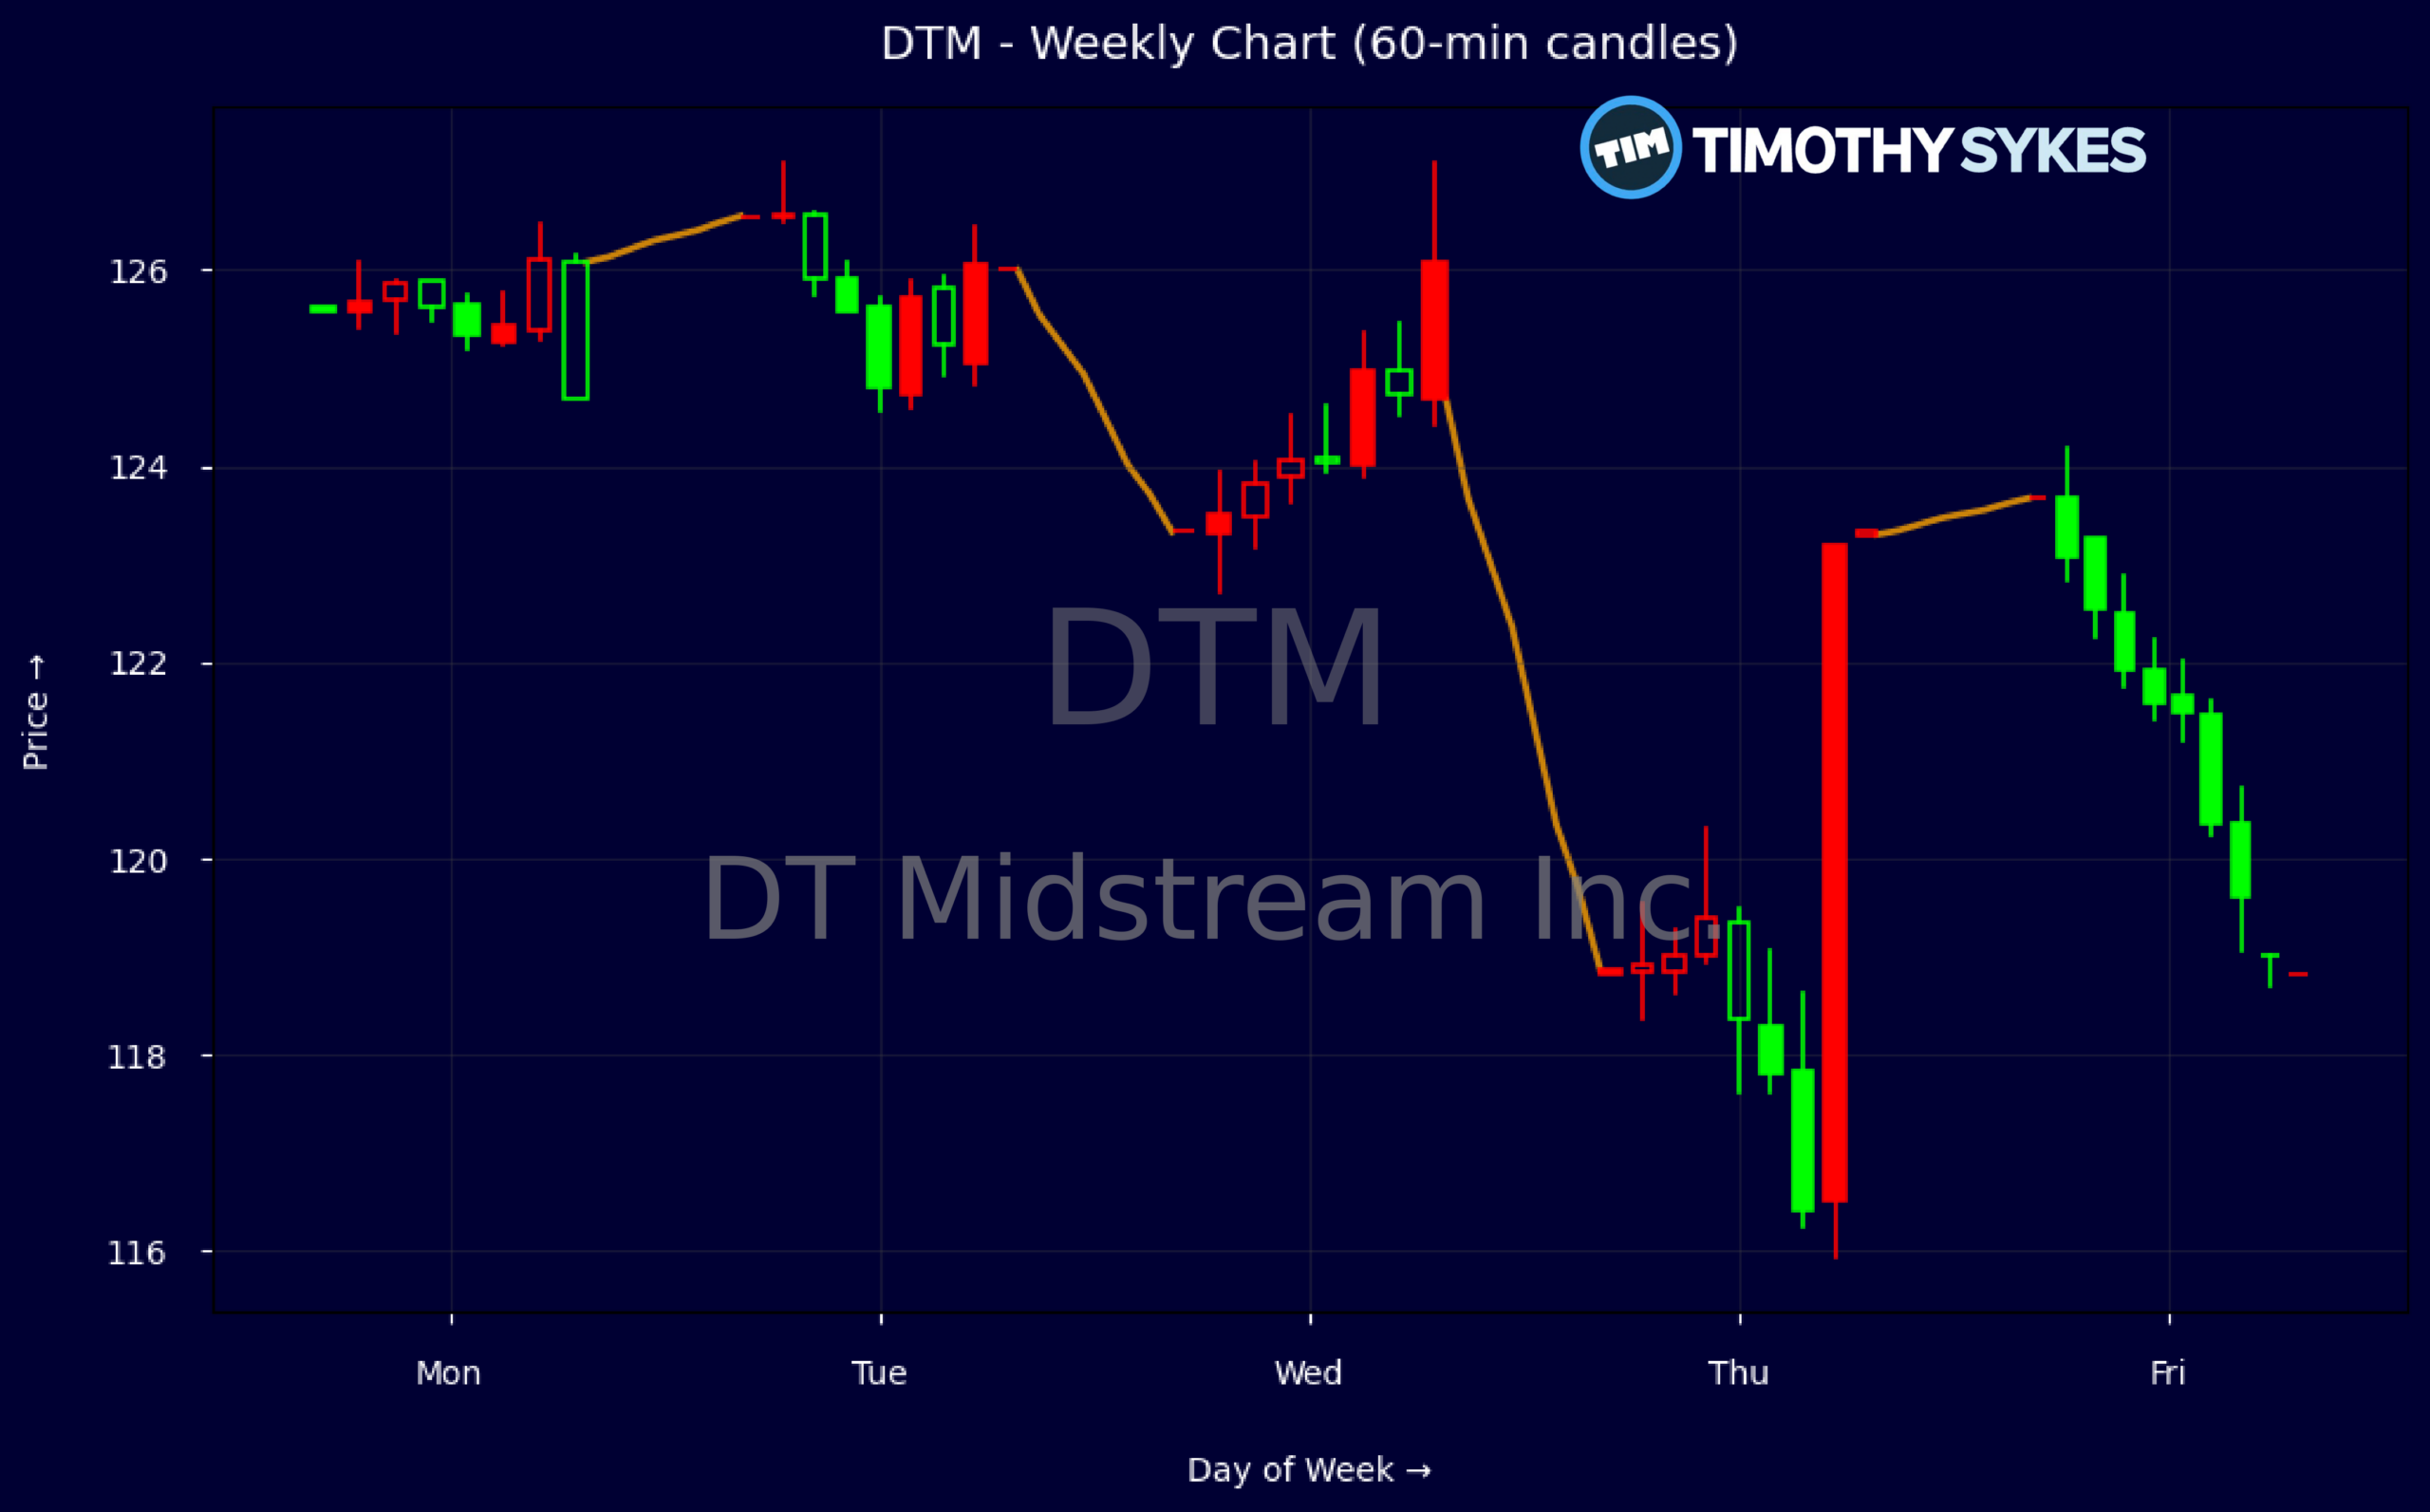
Weekly Update Oct 12 – Oct 16, 2026: On Saturday, October 17, 2026 DT Midstream Inc. stock [NYSE: DTM] is trending up by 4.09%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Energy industry expert:
Analyst sentiment – positive
DT Midstream holds a high-quality, fee-based midstream profile with exceptional profitability: EBIT margin of 61.8% and EBITDA margin of 83.5% are top-tier versus the broader energy infrastructure universe. Mid‑teens revenue CAGR over three years (12.4%) and strong 5‑year growth support its premium multiples (P/E 27.2x, ~9.7x sales). Leverage is conservative with total debt-to-equity of 0.71 and interest coverage of 6.7x, sustaining a ~2.8% dividend yield and visible cash flow growth.
Recent price action shows a sharp reversal from 126.55 to 118.81 before a rebound toward 123.67, indicating a brief shakeout within an ongoing primary uptrend. The tight intraday ranges around 125–126 followed by the swift selloff suggest profit taking on light-to-moderate volume rather than structural distribution. Key tactical level is support at 118–119; sustained closes above 124 open a retest of the 126.50 area, where prior supply sits. Risk-reward favors accumulation near 119 with a stop below 116.
Near-term catalysts are Q3 2026 earnings on October 29 and potential project updates that validate UBS’s view of a robust committed backlog despite temporary EBITDA softness. Street targets ($142–$170) and multiple Buy/Outperform ratings reflect confidence that rising utility and data center gas demand will outgrow sector benchmarks. Versus the broader Energy and Fossil Fuels group, DTM warrants a premium multiple. I see fair value in the $145–$150 range over 12 months, with support at 118 and resistance at 135 then 145.
More Breaking News
Quick Financial Overview
DT Midstream Inc. (DTM) is trading through a choppy but upward-leaning tape. Weekly data show a recent push from the mid-$120s, with prices touching $126.55 before pulling back toward $118.81 and then snapping back to $123.67. That swing tells traders there is active two-sided participation, but buyers are stepping in on dips. The intraday candle, opening near $119.61 and closing at $123.67 after testing down to roughly $119.06, confirms a strong intraday reversal with clear demand absorbing weakness.
On the fundamentals, DTM runs with very high profitability for a midstream name. EBIT margin near 61.8% and EBITDA margin above 80% signal a wide, fee-like model that throws off substantial cash relative to revenue of about $1.243B. Net profit margins in the mid-30% range back up the idea that most of each dollar of sales is dropping to the bottom line. For traders, that kind of margin profile usually supports premium valuation multiples and cushions downside during soft quarters.
Valuation reflects this strength. A price/earnings ratio around 27.2 and price/sales near 9.66 show DTM priced as a quality, stable grower rather than a distressed cyclical. Balance sheet metrics are reasonable, with total debt-to-equity around 0.71 and interest coverage of 6.7, suggesting manageable leverage for an asset-heavy business. Cash generation looks solid, with price-to-cash-flow at 14.3 and dividend yield near 2.85% on a dividend rate of $3.52 per share. For traders, that means the stock has support from income-focused money while still being sensitive to growth expectations and analyst target changes.
Conclusion
DT Midstream Inc. sits at an important crossroads for active traders. On one side, Jefferies, UBS, and Scotiabank all lean bullish with Buy or Outperform ratings and price targets clustered from $150 to $170, anchored in rising utility and data center gas demand and a visible project backlog beyond 2030. On the other side, Scotiabank and Barclays highlight moderating second-half performance, flat-to-down earnings revisions, and the need to prove that DTM can fully capture macro tailwinds in a competitive field.
Recent price action backs this mixed but constructive setup. The sharp intraday rebound from the high-$119 area to a close above $123 shows dip-buying interest, while the weekly slide to $118.81 marks a clear near-term line in the sand. Strong margins, decent leverage, and a steady dividend add a fundamental floor, but a rich multiple leaves the name vulnerable if Q3 2026 numbers come in soft or guidance underwhelms.
For short-term traders, the 2026/10/29 earnings release is the key catalyst. The focus should be on Q3 EBITDA versus expectations, commentary around maintenance and seasonal softness, and updates on the committed backlog and ESG-linked growth strategy. As millionaire penny stock trader and teacher Tim Sykes, says, “Preparation plus patience leads to big profits.”. That mindset is crucial here: doing the homework on key levels, scenarios, and risk parameters ahead of time, then waiting for high-quality setups around the catalyst, is what separates disciplined trading from guesswork. As I tell my students: “The edge is not in predicting the news, it’s in knowing exactly which levels and reactions you’re willing to trade when the news hits.”
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply