Capri Holdings Limited stocks have been trading up by 16.3 percent amid intensified acquisition speculation and renewed luxury retail optimism.
What Traders Need To Know
- Fiscal Q2 adjusted EPS of $0.42 doubled the $0.21 consensus, with revenue near $809M also ahead of estimates, signaling a sharp upside surprise for Capri Holdings Limited.
- Management cited steady monthly improvement and early wins in product and brand elevation, raising the annual outlook and flagging a likely second-half turnaround.
- Fiscal 2027 targets now call for EPS of about $2.20 and revenue of roughly $3.42B, both slightly above Wall Street expectations for CPRI.
- Q3 guidance pegs EPS at $0.95, near consensus, on revenue of $1.005B, just under the $1.02B the Street was modeling.
- Shares of Capri Holdings jumped roughly 15–16% after the print, building on premarket gains of more than 6% as traders repriced the turnaround story.
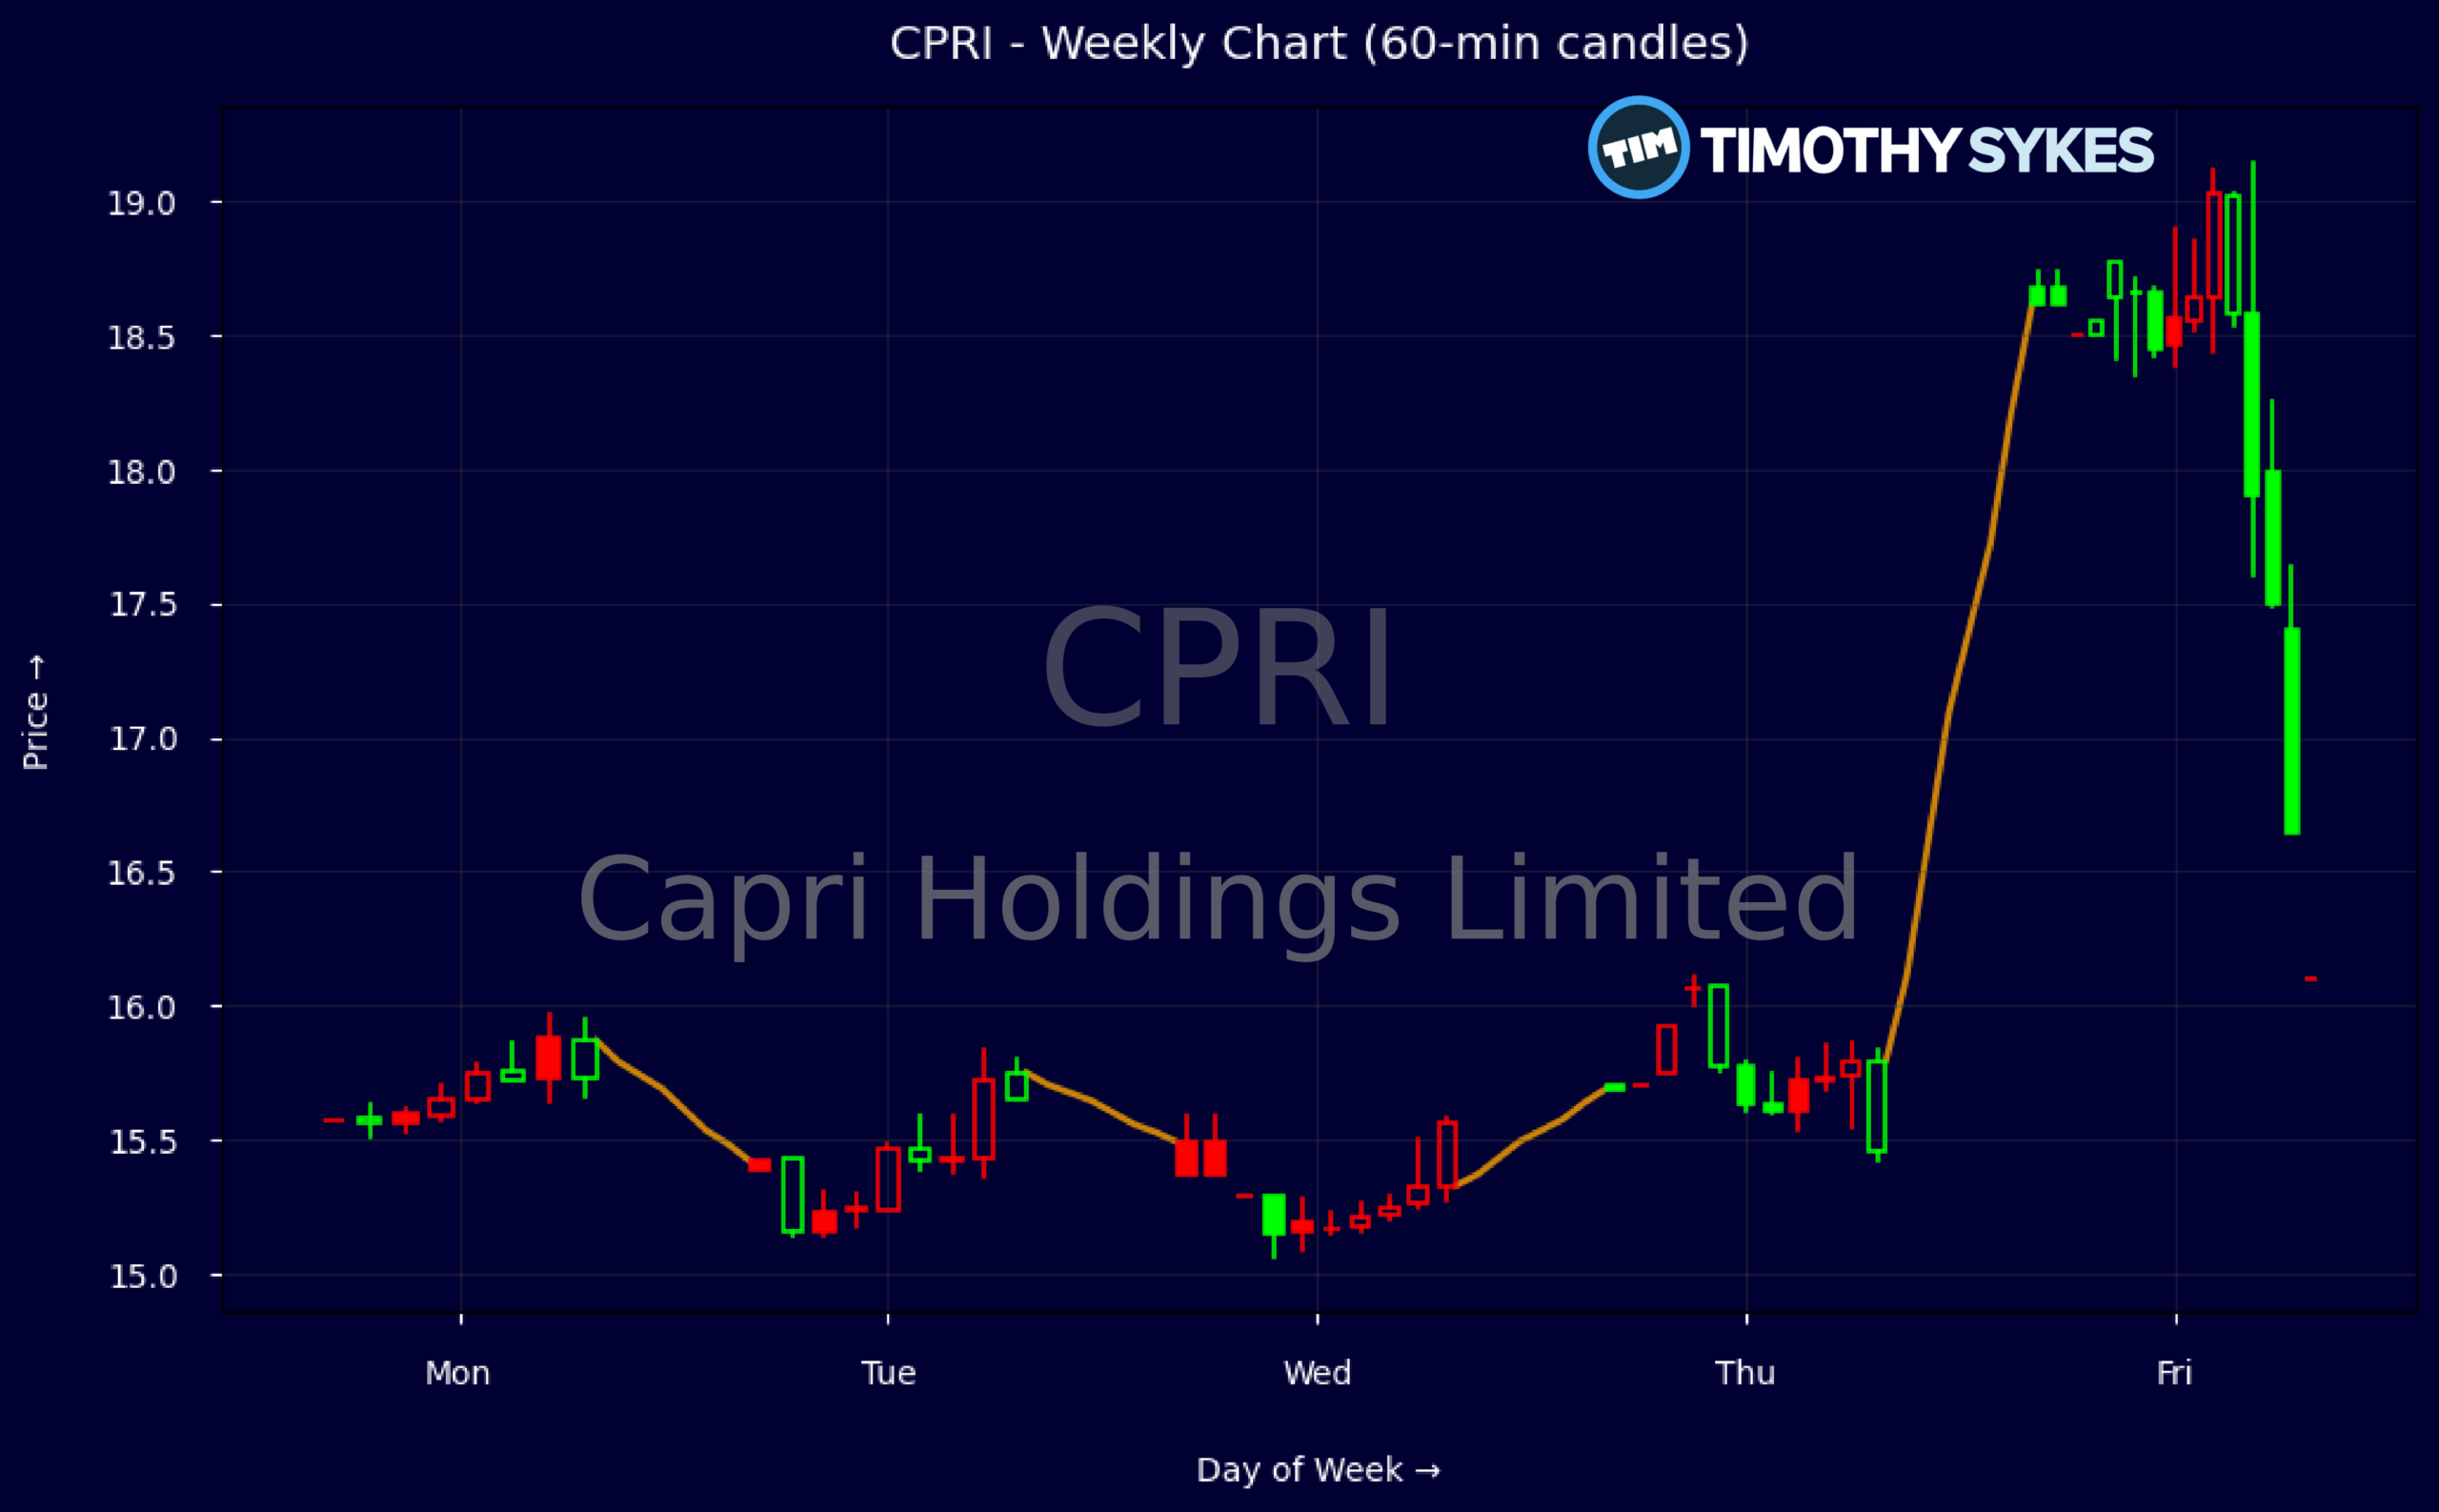
Weekly Update Oct 26 – Oct 30, 2026: On Sunday, November 01, 2026 Capri Holdings Limited stock [NYSE: CPRI] is trending up by 16.3%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Consumer Discretionary industry expert:
Analyst sentiment – positive
Capri’s fundamentals show a challenged but stabilizing luxury portfolio. Revenue contraction over 3–5 years (-14% / -7%) highlights brand maturity and execution issues, yet 62.7% gross margin and an improving 6.7% EBITDA margin confirm intact brand pricing power. Leverage is elevated (total debt/equity 10x, LT debt/capital 89%) but interest coverage at 3.8x and strong Q1 FCF of $48M limit near-term balance sheet risk. Valuation at 0.5x sales and 5.4x FCF already discounts structurally low growth.
Technically, the dominant near-term trend has flipped bullish. The stock broke from mid-15s consolidation to close the week at 18.68, a sharp momentum expansion confirmed by heavy post-earnings volume on 5‑minute candles and repeated buying into minor intraday dips. The actionable level is $16.00–16.25, now primary support and an attractive pullback buy zone. As long as price holds above $16 on a weekly close, upside extension toward the low‑20s remains favored.
Earnings and guidance revisions are the key near-term catalysts. A 100% upside EPS surprise, sequential improvement commentary, and FY27 EPS/revenue guidance above consensus position Capri ahead of most discretionary peers, which are generally guiding cautiously on macro and traffic. In the Retail–Discretionary subset, CPRI now screens as a higher‑beta turnaround rather than a secular decliner. Near term, I see upside to $22 with support at $16 and resistance at $20, then $22–23.
More Breaking News
Quick Financial Overview
Capri Holdings Limited just delivered the kind of earnings shock that forces traders to re-mark their charts. Fiscal Q2 adjusted EPS landed at $0.42 versus $0.21 expected, a 100% upside surprise, while revenue around $809M beat estimates near $786M–$781M. That beat came even as revenue remains in a downtrend, with trailing annual sales of about $3.47B and three- and five-year revenue growth both negative. The message: earnings power is stabilizing faster than top-line growth.
On the weekly tape, CPRI spent several days coiling near $15.30–$15.60 before exploding to an $18.77 high on 2026/10/30, closing the day near $18.68. That is a clean upside break of the recent range, with a roughly 20% push off the prior week’s lows in a straight line. Intraday, the 5‑minute candle shows a wide $17.60–$19.14 range, but closing back near $18.68 suggests strong dip buying rather than a blow‑off top.
Fundamentals back the move but also define risk. Capri Holdings Limited is running a rich 62.7% gross margin, yet EBIT margin is only 2.4%, showing how much leverage sits in SG&A and brand spending. A price-to-sales near 0.49 and price-to-free-cash around 5.4 imply the market had deeply discounted the story before this quarter. At the same time, financial strength metrics show pressure: total debt-to-equity over 10, a leverage ratio above 23, and a quick ratio of 0.1 mean CPRI is not a fortress balance sheet. Cash flow from operations of $73M against $25M in capex last quarter supports free cash flow, but traders must respect the debt load.
Conclusion
Capri Holdings Limited just flipped the script on a beaten-down luxury name, at least in the short term. A 100% upside EPS surprise, revenue ahead of estimates, and a swing from loss to profit have jolted sentiment. The stock’s surge from the mid‑$15s to the high‑$18s, plus an intraday spike above $19, tells you shorts were caught leaning the wrong way and momentum players piled in. Layer on fiscal 2027 guidance for $2.20 in EPS and $3.42B in revenue, both modestly ahead of the Street, and CPRI now trades like an active turnaround, not a broken brand.
For traders, the key is separating one great quarter from a lasting trend. Management is talking up sequential improvement and stronger product and brand positioning, but near‑term Q3 revenue guidance is still slightly under consensus, and longer-term revenue growth remains negative. High leverage and thin operating margins keep execution risk front and center. CPRI offers clear trading opportunity around volatility, technical breakouts, and guidance updates, not a set‑and‑forget story. In this type of volatile turnaround tape, discipline matters as much as direction. As millionaire penny stock trader and teacher Tim Sykes says, “Be patient, don’t force trades, and let the perfect setups come to you.” That mindset is especially relevant here, where chasing every spike can be far riskier than waiting for clean confirmation around key levels and fresh guidance.
Capri Holdings Limited now sits in a “prove it” zone where every quarter will be judged against these higher expectations. As I tell my own students, “You trade a turnaround like CPRI by respecting both the breakout and the baggage — ride the strength, but never ignore the risk hiding in the balance sheet.”
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply