Transocean Ltd (Switzerland) stocks have been trading up by 6.58 percent following strong offshore drilling contract wins, boosting optimism
Key Takeaways
- Transocean locked in roughly $1.1B of new firm backlog in Norway, including a ~$62M contract for Transocean Norge with A/S Norske Shell and final Equinor approval on a multi‑rig deal.
- The company added about $550M of firm backlog for the Deepwater Proteus and Deepwater Conqueror drillships in the U.S. Gulf, with multi‑year work starting in 2027.
- Brazil’s regulator cleared the Valaris–Transocean merger without restrictions, setting up a Q4 closing for the all‑stock combination.
- Transocean upsized and extended its main credit facility to $750M out to 2031 and redeemed $165M of 8% notes, trimming interest costs by roughly $22M.
- A law firm is reviewing whether Valaris is undervalued in the all‑stock sale to Transocean, which will pay 15.235 RIG shares per VAL share.
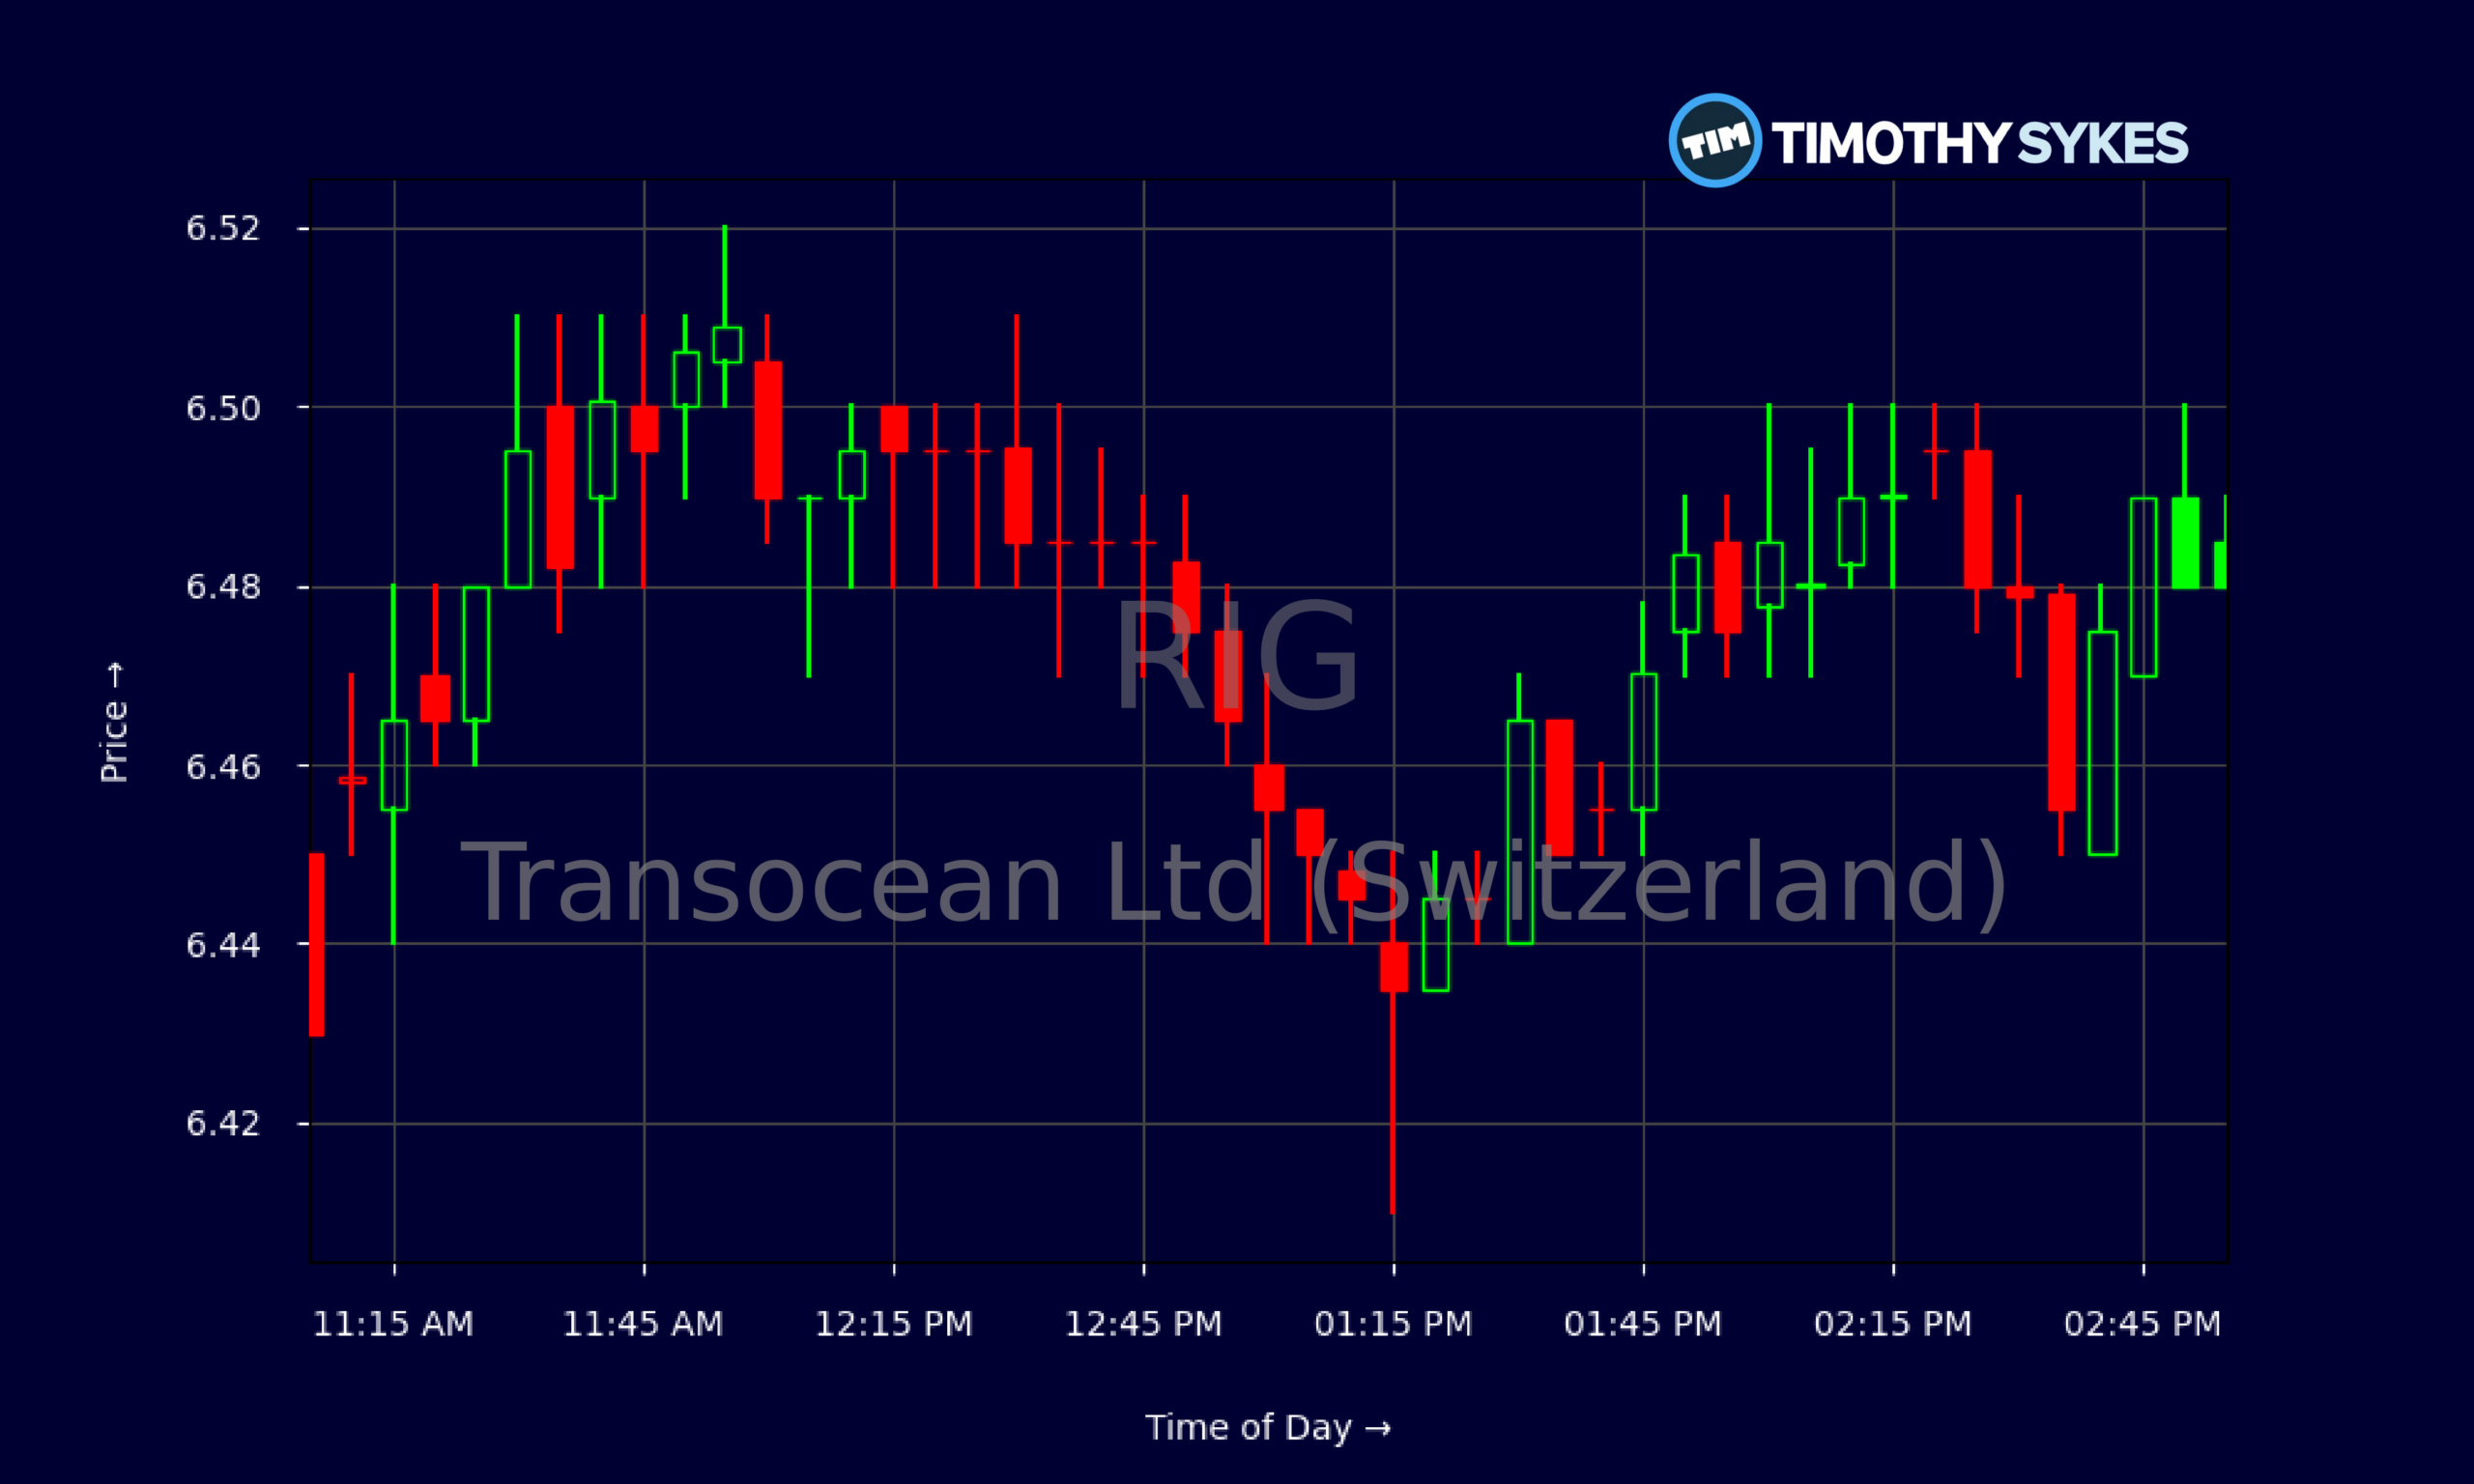
Live Update At 15:02:40 EDT: On Friday, October 23, 2026 Transocean Ltd (Switzerland) stock [NYSE: RIG] is trending up by 6.58%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
RIG has been grinding higher on the chart. Over the past few weeks, Transocean has moved from the $5.20s into the mid‑$6s, with the latest close around $6.48 after tagging an intraday high near $6.52. That’s a steady uptrend, not a one‑day spike, which tells traders real buyers are stepping in on dips.
Intraday, RIG has been trading in a tight band between roughly $6.35 and $6.52, with repeated tests of the high of day but no heavy rejection. That kind of controlled range often signals accumulation rather than wild speculation. For day traders, that means clean levels to trade against; for swing traders, it hints at a potential base forming above $6.
More Breaking News
Fundamentals are still in turnaround mode. Transocean generated about $3.97B in annual revenue with roughly 21.5% gross margin, but headline profit margins remain negative on a trailing basis and returns on equity are deep in the red. The latest quarterly numbers, though, show progress: EBITDA of $312M, operating income of $154M, and operating cash flow of $236M. Free cash flow of $212M in the recent quarter gives RIG some real flexibility to chip away at debt and ride this offshore up‑cycle.
Why Traders Are Watching RIG Right Now
Transocean is suddenly stacking catalysts, and traders are paying attention. On the contract side, RIG just added roughly $1.1B in firm backlog in Norway alone. That bundle includes a ~$62M, 120‑day, two‑well job for Transocean Norge with A/S Norske Shell plus Equinor’s final sign‑off turning about $1.0B of earlier Norway semisubmersible agreements into locked‑in backlog. For traders, that’s not just a headline; it’s visibility. More contracted days mean less guessing on future revenue and rig utilization.
RIG didn’t stop there. In the U.S. Gulf of Mexico, Transocean secured around $550M in firm backlog for the Deepwater Proteus and Deepwater Conqueror. These are ultra‑deepwater drillships, and the new multi‑year campaigns kick off in early and mid‑2027 as direct continuations of the rigs’ current programs. Direct continuation is critical. It limits idle time, keeps crews and equipment working, and tends to support stronger dayrates. That’s exactly what traders want to see in a cyclical name tied to offshore drilling.
The tape has responded. When the Norge contract hit, RIG traded about 0.7% higher pre‑market even as the broader energy space sagged. After the $550M U.S. Gulf news, the stock popped more than 1% pre‑market despite softer oil benchmarks. That tells short‑term traders something important: backlog headlines are acting as real trading catalysts for RIG, sometimes overpowering the macro trend in crude and sector ETFs.
Layer on the Valaris deal, and the story gets bigger. Brazil’s competition authority cleared the Valaris–Transocean combination without conditions, leaving all regulatory boxes checked and putting the Q4 closing track in play. A clean approval with no remedies is a strong read‑through for the combined offshore giant’s competitive footprint. For active traders, that reduces deal‑break risk and shifts focus toward integration potential, scale, and what the post‑merger fleet can earn in a tightening deepwater market.
Conclusion
RIG is not a quiet value plodder right now; it’s a contract‑and‑capital‑structure story playing out in real time. On one side, Transocean is loading its backlog with about $1.1B of fresh Norwegian work and roughly $550M from two high‑spec U.S. Gulf drillships. Those numbers push firm work visibility well into 2027 and help smooth out cash flow in a notoriously boom‑bust industry.
On the other side, RIG is addressing its balance sheet. The company amended and restated its main credit facility, expanding the revolver to $750M and pushing maturity from 2028 to 2031, contingent on closing the Valaris acquisition. The revolver was oversubscribed, a quiet but powerful signal that banks are comfortable with Transocean’s credit risk after the merger. Retiring $165M of 8% Aquila notes and saving around $22M in future interest adds another layer of de‑risking and free‑cash‑flow upside.
The Valaris acquisition still carries some noise. A law firm is probing whether Valaris is being short‑changed at 15.235 RIG shares per VAL share. For traders, that’s headline risk more than thesis risk at this point, but it’s one more variable to track into the Q4 closing window.
In this type of name, trend and catalysts matter more than hope. RIG’s price action, rising backlog, and sharper balance sheet give traders a clear framework: map key support and resistance, time entries around contract and fleet‑status headlines, and respect the volatility. As millionaire penny stock trader and teacher Tim Sykes says, “Cut losses quickly, let profits ride, and don’t overtrade.” As Tim Sykes likes to say, “The market doesn’t care about your opinion, it cares about your discipline.” RIG is giving disciplined traders plenty to study, and plenty to trade, as this offshore cycle heats up.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply