Boot Barn Holdings Inc. stocks have been trading up by 15.1 percent amid upbeat consumer demand and strong earnings momentum.
Key Takeaways For BOOT Traders
- Fiscal Q2 EPS of $1.73 topped expectations near $1.63–$1.64 on slightly better‑than‑forecast $581.8M revenue.
- Same-store sales rose 1.4%, powered by 5.2% e‑commerce growth, while merchandise margins expanded 190 basis points thanks to lower freight, tariff refunds, and stronger mix.
- FY27 guidance calls for EPS of $8.72–$9.00 on $2.565B–$2.593B revenue, implying 14–15% growth but landing just under prior Street forecasts.
- A fresh $400M share repurchase authorization adds firepower for Boot Barn to buy back stock.
- Needham, UBS, and TD Cowen all rate BOOT shares Buy, even after trimming price targets to $150, $232, and $160, respectively.
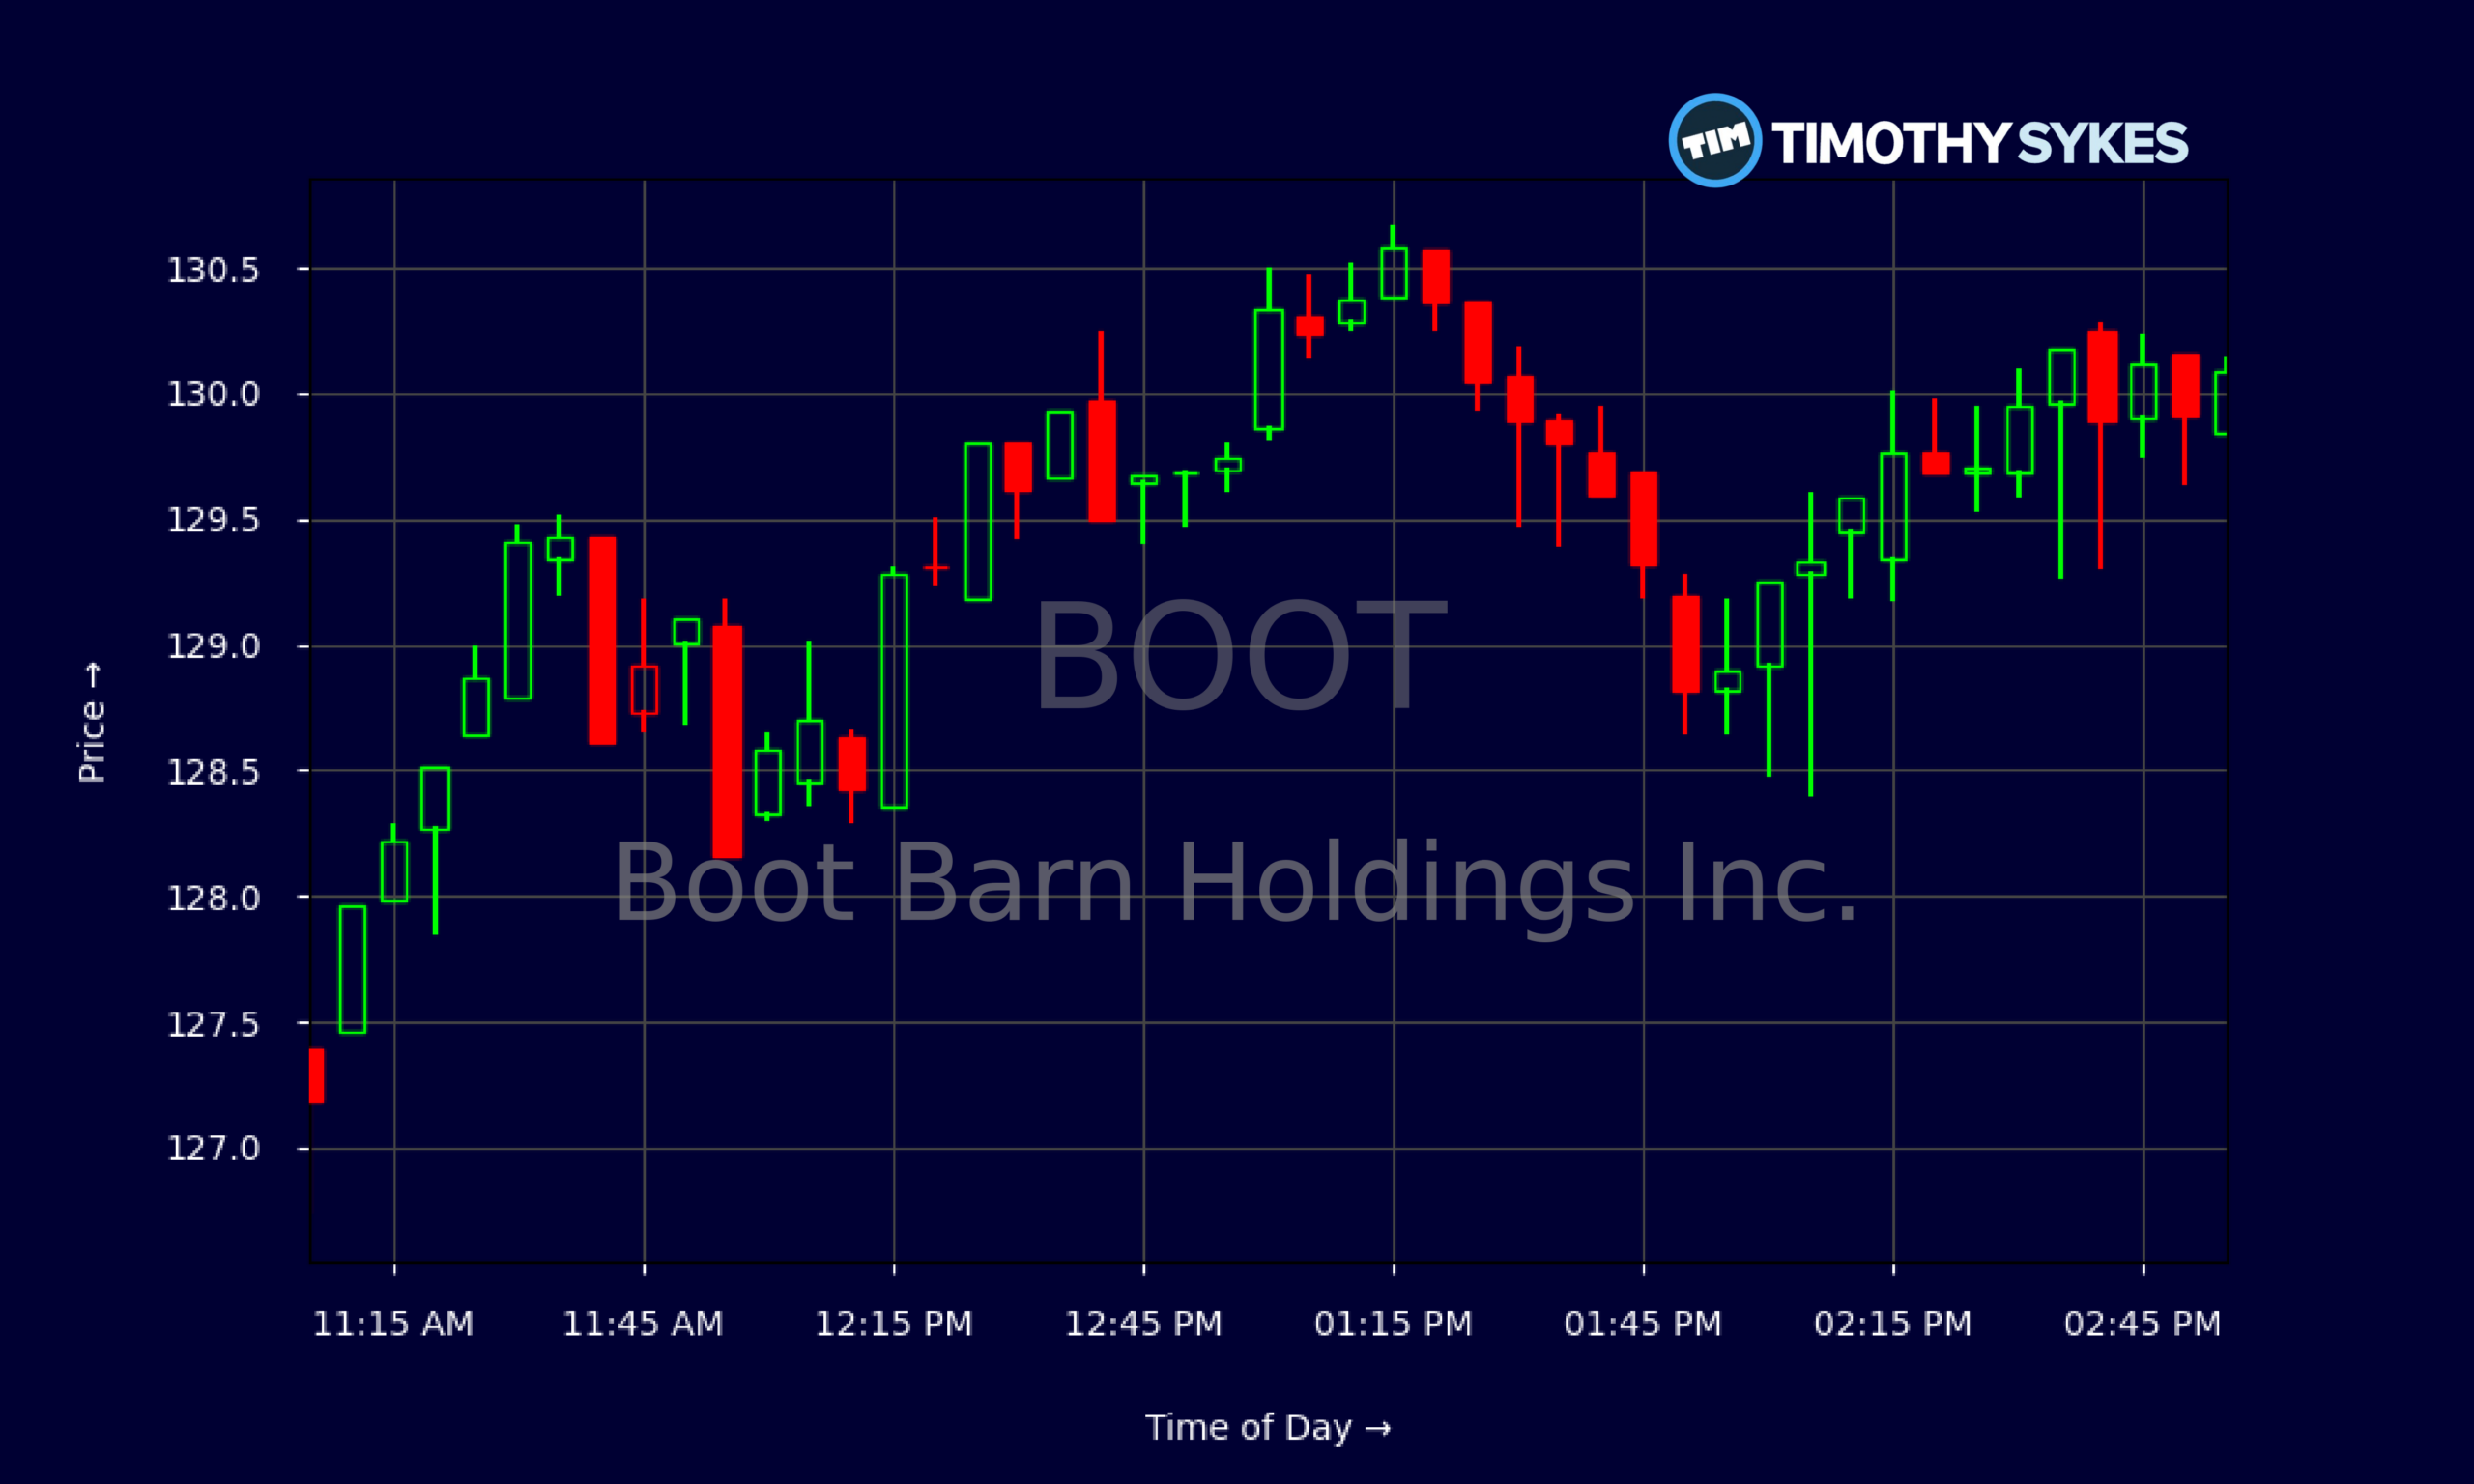
Live Update At 15:02:34 EDT: On Thursday, October 29, 2026 Boot Barn Holdings Inc. stock [NYSE: BOOT] is trending up by 15.1%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
BOOT just delivered the kind of quarter that keeps bullish traders leaning in. Boot Barn posted fiscal Q2 revenue of $581.8M, a touch ahead of expectations, and turned that into diluted EPS of $1.73, beating the roughly $1.64 consensus. In retail, small beats matter because they show execution, not luck.
Under the hood, the story looks stronger. Boot Barn’s gross margin sits near 38.5%, and in the quarter merchandise margin expanded by 190 basis points as lower freight, tariff refunds, and a better product mix kicked in. With EBIT margin around 13.8% and profit margin over 10%, BOOT is not just selling more cowboy boots — it is doing it profitably.
More Breaking News
On the tape, traders saw that in real time. After closing at $113.30 on 2026/10/28, BOOT ripped to a $130.41 close on 2026/10/29, with the intraday 5‑minute chart showing steady grinding strength rather than a one‑and‑done spike. At a roughly 15x price‑to‑earnings multiple and 1.55x price‑to‑sales, Boot Barn sits well below its 5‑year peak multiples, even while generating returns on equity around 19%. For active traders, that combo of earnings strength, expanding margins, and a breakout daily candle is exactly the kind of setup that draws momentum and swing trading interest.
Why Traders Are Watching BOOT After This Breakout
BOOT is back on the radar because the fundamentals and the chart are finally lining up. Boot Barn didn’t just beat on EPS; management also talked up strong new‑store performance, a growing national brand, and optimism into the holiday season. They’re leaning on refreshed assortments, better in‑store presentations, expanded marketing, and the relaunch of Boot Barn Workforce. For traders, that reads like a catalyst stack heading into the most important shopping window of the year.
Longer term, Boot Barn laid out FY27 guidance that still looks ambitious. The company is targeting EPS of $8.72–$9.00 and revenue of $2.565B–$2.593B, roughly 14–15% above FY26. That plan includes 75–80 new stores and another 140 basis points of merchandise margin expansion, helped again by tariff refunds and mix. Yes, those numbers sit slightly under prior consensus, but the direction is still up and to the right. BOOT is effectively telling the Street: growth is intact, just more realistic.
On the Street side, Needham stepped in with a fresh Buy and a $150 target, calling the recent selloff a buying opportunity and pointing to Boot Barn’s dominant niche in country‑western workwear. UBS and TD Cowen cut their targets but stayed in the Buy camp, with UBS at $232 and TD Cowen at $160. The message is clear — expectations are being reset, not abandoned.
There are still near‑term wrinkles. UBS flags soft comparable‑sales trends and thinks Q3 comps may be only flat to up 2%, while industry data show low single‑digit declines so far. That’s exactly the kind of detail short‑term BOOT traders should track: if comps slide to the low end, the stock can whip around. But if holiday traffic beats that “low bar,” there’s room for upside surprises.
Layer on the new $400M share repurchase plan and Boot Barn just gave itself a serious buyback bid under the stock. For traders, an active buyback often acts like a safety net on sharp dips and can quietly boost EPS over time.
Conclusion
BOOT’s latest move is a textbook example of how sentiment can flip when numbers back the story. Boot Barn is showing real revenue growth, widening margins, and disciplined cost control, all while still trading at mid‑teens earnings multiples. The balance sheet is solid, with manageable leverage, a current ratio around 2.5, and strong interest coverage. That gives Boot Barn room to keep opening stores, funding marketing, and executing that $400M repurchase plan without over‑stretching.
The Street is sending a mixed but tradable message. Needham, UBS, and TD Cowen all still like the name, but they’re also telling traders to respect softer near‑term comps and slightly trimmed FY27 expectations. That tension — strong long‑term story, cautious short‑term tape — is exactly where so many of the best trading opportunities show up.
For active BOOT traders, the game plan is simple: track comps, watch how the holiday quarter develops, and study how price reacts around key support and resistance after this earnings‑driven breakout. As Tim Sykes likes to say, “The market doesn’t reward hope, it rewards preparation.” As millionaire penny stock trader and teacher Tim Sykes, says, “There is always another play around the corner; don’t chase just because you feel FOMO.”. Use Boot Barn’s clear guidance, analyst targets, and the recent surge in trading action as data to build a plan — not as a reason to chase blindly. This coverage of BOOT is for educational and research purposes only, and every trader still needs to do their own homework before risking a single dollar.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply