AT&T Inc. stocks have been trading up by 3.93 percent amid strong investor optimism over its latest strategic network expansion.
Key Takeaways
- Q3 results from AT&T Inc. topped expectations with adjusted EPS of $0.65 vs $0.60 and revenue of $32.3B vs $31.65B, supported by 379,000 postpaid phone net adds and 0.92% churn.
- Management raised 2026 adjusted EPS guidance to about $2.40 and reiterated plans for EBITDA growth and strong free cash flow, signaling rising confidence in AT&T’s earnings power.
- Q4 free cash flow guidance of roughly $6B, versus $4.2B last year, underpins AT&T’s plan to return $45B+ to shareholders during 2026–2028 while driving leverage toward about 2.5x by 2029.
- The company is leaning into fiber and modern broadband, reporting its strongest service revenue growth in over four years, targeting $4B in annual cost savings by 2028, and retiring legacy copper faster.
- A $2B divestiture of AT&T Mexico to Grupo Televisa and Fintech simplifies AT&T’s portfolio and adds balance-sheet flexibility ahead of heavier capital returns.
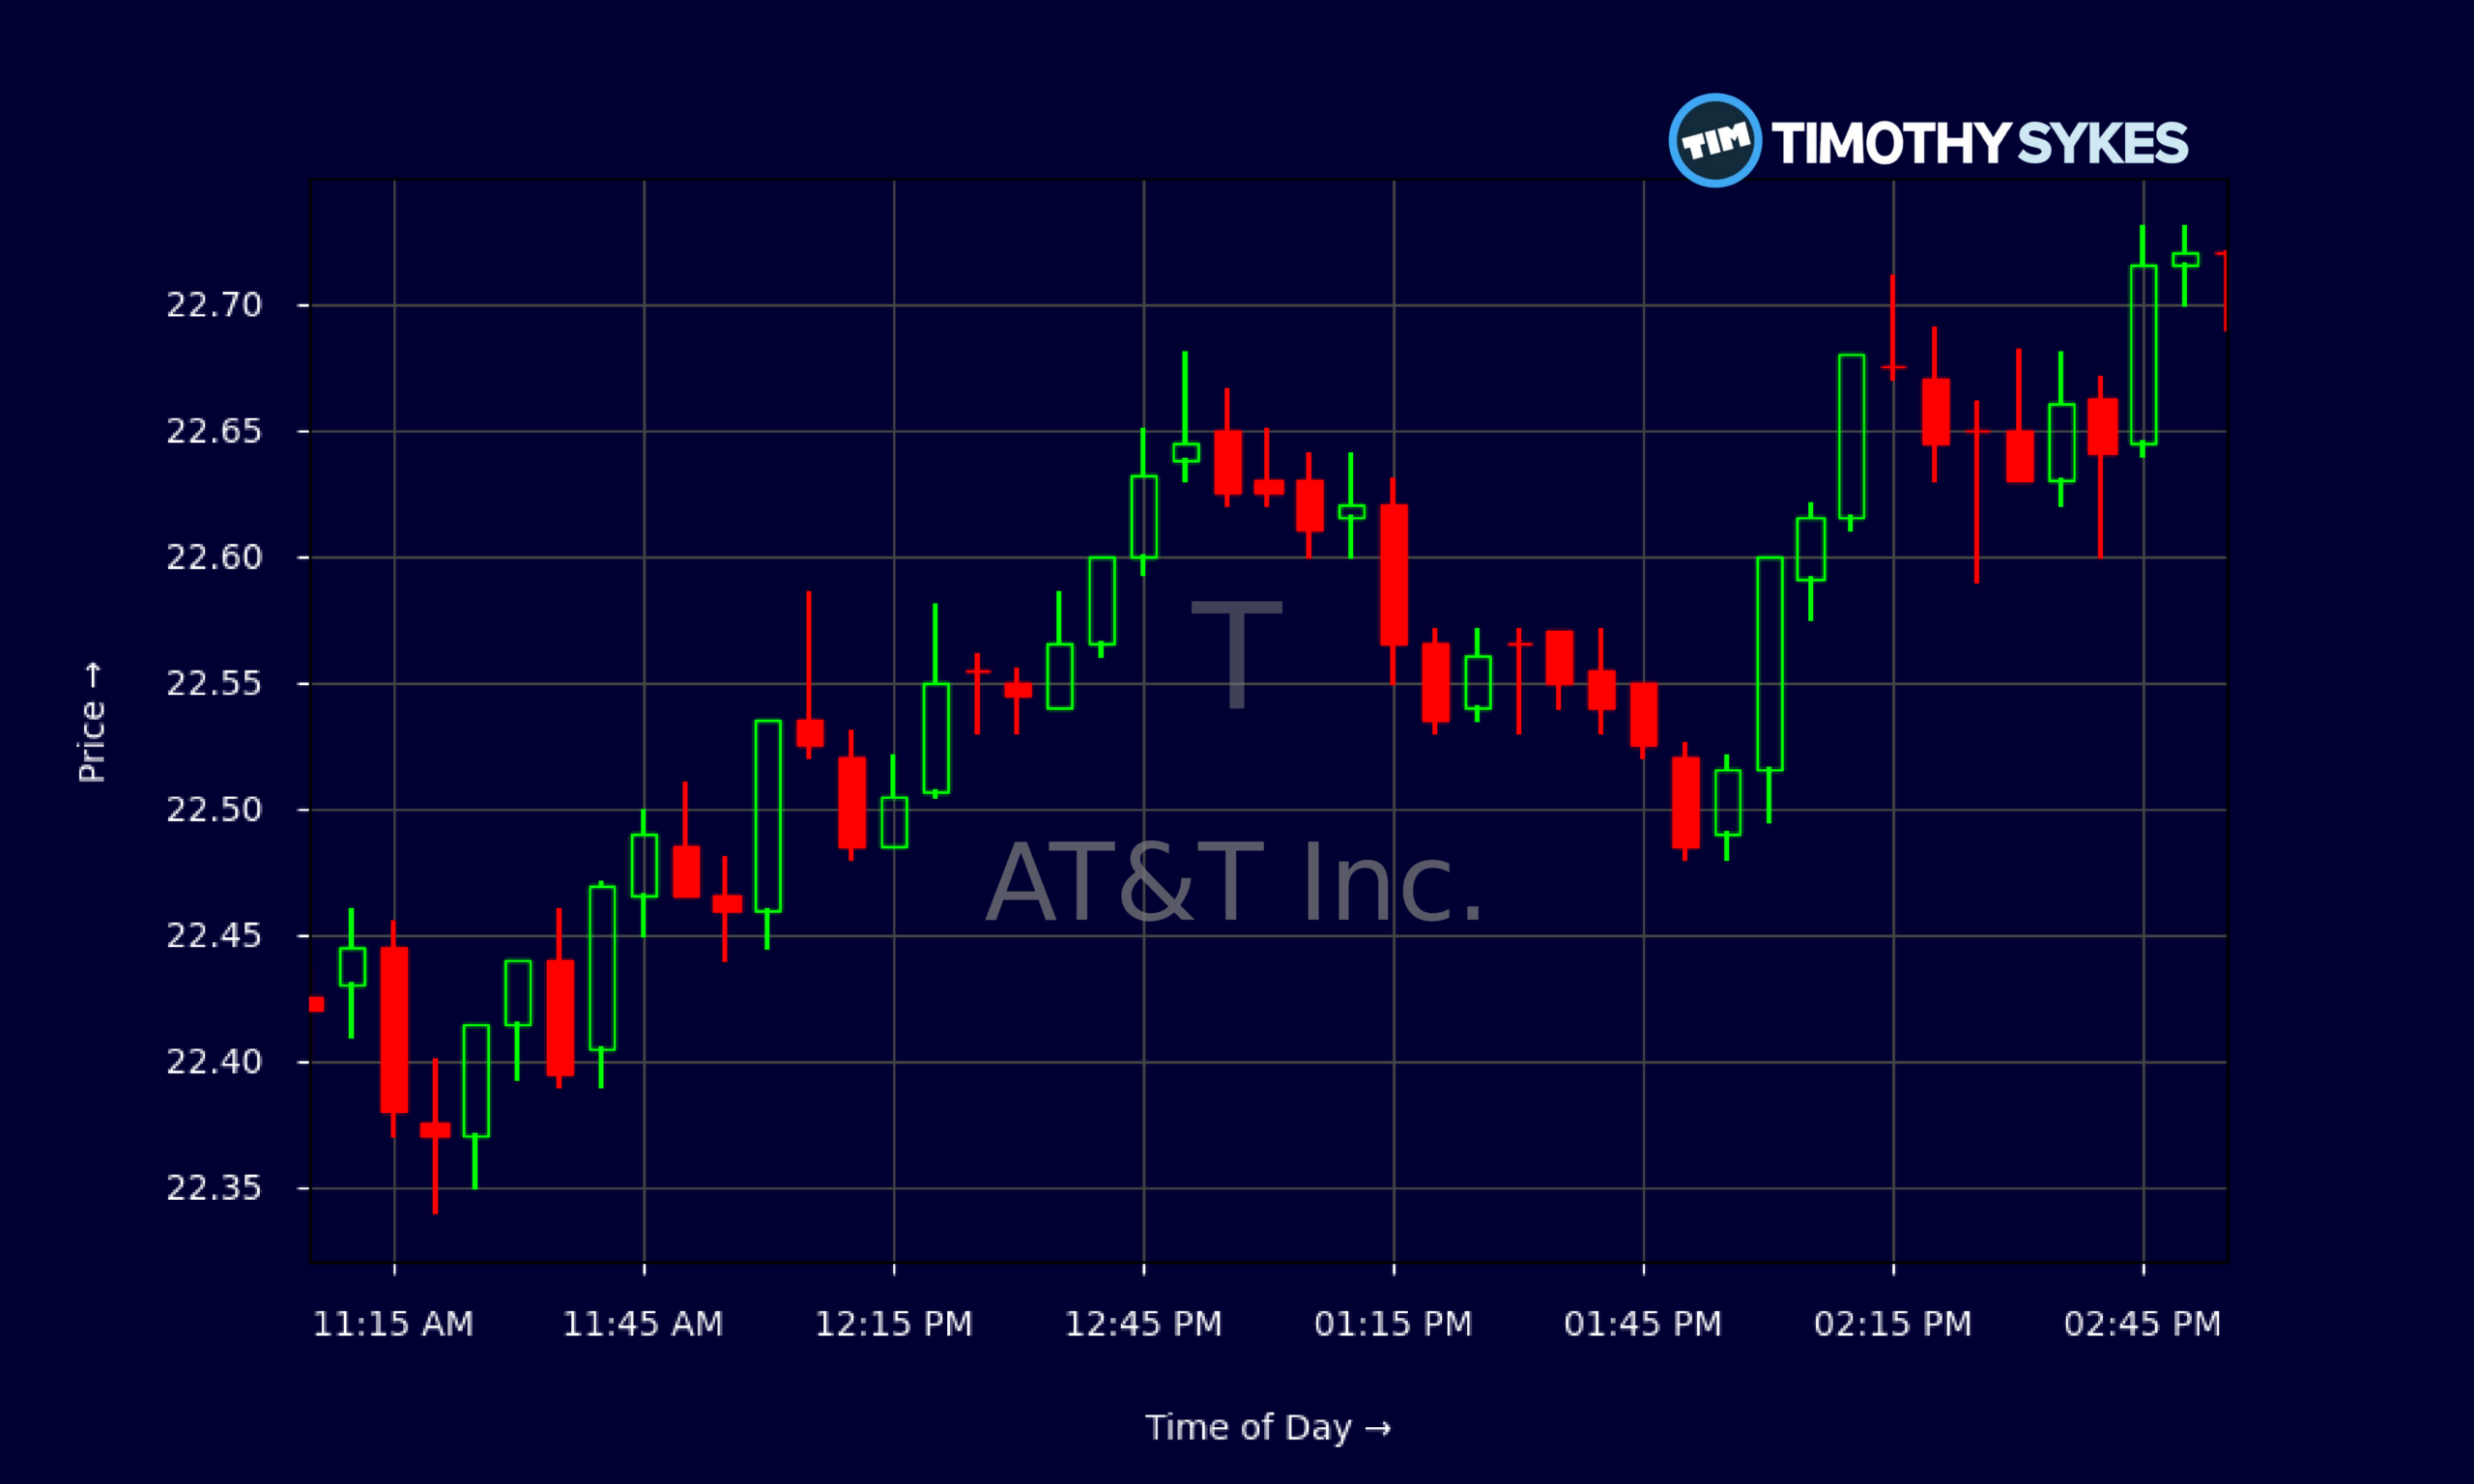
Live Update At 15:02:16 EDT: On Thursday, October 22, 2026 AT&T Inc. stock [NYSE: T] is trending up by 3.93%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AT&T Inc. just reminded the market that boring can still move the tape. T delivered Q3 adjusted EPS of $0.65, beating the $0.60 consensus, on revenue of about $32.3B versus expectations near $31.65B. For a mature telecom, those beats matter because they back up the cash-flow story traders care about.
Service revenue is re-accelerating, helped by more than 1 million Advanced Connectivity net adds for a second straight quarter and record fiber plus fixed wireless additions. AT&T’s profitability profile is still solid: EBIT margin around 26% and EBITDA margin above 40% give T room to fund capex, service debt, and pay a dividend that currently yields about 5%.
On the chart, T has been choppy. The daily data show a slide from the mid-$24s to the low $22s, then a sharp bounce to a $22.77 close after earnings. Intraday, T stair-stepped higher most of the session, holding higher lows and squeezing into the close – classic earnings-reversal price action.
More Breaking News
With a P/E near 7 and price-to-free-cash-flow under 6, AT&T is priced like a utility, not a growth story. For traders, that disconnect between improving fundamentals and cautious sentiment is exactly what creates opportunity and volatility.
Why Traders Are Watching AT&T Now
AT&T Inc. is finally stringing together the kind of quarters that force traders to pay attention. T didn’t just beat on Q3 EPS and revenue; it also raised its 2026 adjusted EPS outlook to about $2.40, above both its prior range and Wall Street’s $2.34 consensus. That is management putting its reputation on the line three years out.
Under the hood, AT&T is shifting from legacy to growth. The company is logging its strongest consolidated service revenue growth in more than four years, driven by Advanced Connectivity and a record quarter for fiber and fixed wireless internet. On the Q3 call, AT&T’s CEO pointed to record fiber reach and a stronger spectrum position, backed by tiered introductory pricing that aims to keep subscriber growth humming without blowing up margins.
Cost discipline is the other pillar. AT&T told the market it is on track for $4B in annual cost savings by year-end 2028. A big piece of that is network modernization: T plans to mothball copper-based legacy services in 50% of wire centers outside California by 2027 and nearly all by 2029. Less copper means lower maintenance, fewer truck rolls, and better broadband economics.
At the same time, AT&T is cleaning up its portfolio. The planned $2B sale of AT&T Mexico to Grupo Televisa and Fintech, plus potential contingent benefits, frees up capital and management focus for U.S. fiber and 5G. Add in Q4 free cash flow guidance of about $6B – far above last year’s $4.2B – and the company has the fuel to support its pledge to return more than $45B to shareholders in 2026–2028 while working leverage down toward roughly 2.5x by 2029.
Yet the tape has not been straight up. AT&T’s stock dropped more than 5% even after this stronger Q3 and raised outlook, as traders keyed in on softer-than-hoped postpaid phone net adds and fierce wireless competition. Goldman Sachs and Scotiabank trimmed price targets, even as they kept positive ratings. That combination – improving fundamentals, skeptical market – is exactly why active traders are locking T onto their screens right now.
Conclusion
For traders, AT&T Inc. sits at the crossroads of cash flow and narrative. On one side, you have hard numbers: Q3 beats on EPS and revenue, $5.0B in free cash flow in the quarter, and guidance for about $6B in Q4. On the other, you have a market still focused on competitive pressure, subscriber trends, and fears around new satellite entrants.
Analysts are not ignoring the risks. Postpaid phone growth missed some expectations, customer acquisition costs are climbing, and the wireless field remains crowded. SpaceX’s spectrum move rattled the whole carrier group, including T. But research like MoffettNathanson’s – which downplays Starlink’s near-term threat to AT&T, T-Mobile, and Verizon – shows the gap between fear and fundamental reality.
AT&T is trying to close that gap with execution: record fiber expansion, multi-year cost saves, copper shutdowns, a $2B Mexico exit, and a roadmap to return $45B+ to shareholders from 2026 to 2028 while cutting leverage. The balance sheet is not perfect, but directionally it is improving.
For active traders, the lesson is simple. T is no longer just a sleepy dividend name; it is a cash-flow machine in the middle of a multi-year pivot. As millionaire penny stock trader and teacher Tim Sykes, says, “Small gains add up over time; focus on building wealth gradually, not chasing jackpots.”. As Tim Sykes loves to say, “The market rewards preparation, not prediction.” With AT&T reshaping its business and sentiment still mixed, the edge goes to traders who actually study the earnings, watch the price action, and stay disciplined on every T trade.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply