Meta Platforms Inc. stocks have been trading up by 2.15 percent amid bullish sentiment on its AI-driven advertising growth.
Key Takeaways Traders Should Watch
- Wall Street pushed META targets as high as $1,000 after Q3, leaning into the company’s AI-driven growth story despite elevated capex and legal noise.
- The company delivered 26% revenue growth and 265% EPS growth even while absorbing a $9.9B teen-mental-health legal charge, with AI products already lifting ad performance.
- Daily usage across META apps hit 3.64B people, with record engagement on Facebook and Instagram and a plan to make Muse over 10x more cost-efficient within a year.
- Major firms like Pivotal Research, Citi, Barclays, UBS, Goldman Sachs, Morgan Stanley, and others reiterated Buy/Overweight views, clustering price targets roughly between $800 and $1,000.
- A new non-voting Class C share, effectively a 2-for-1 split in 2027, aims to fund AI and infra growth while easing near-term equity overhang concerns for META traders.
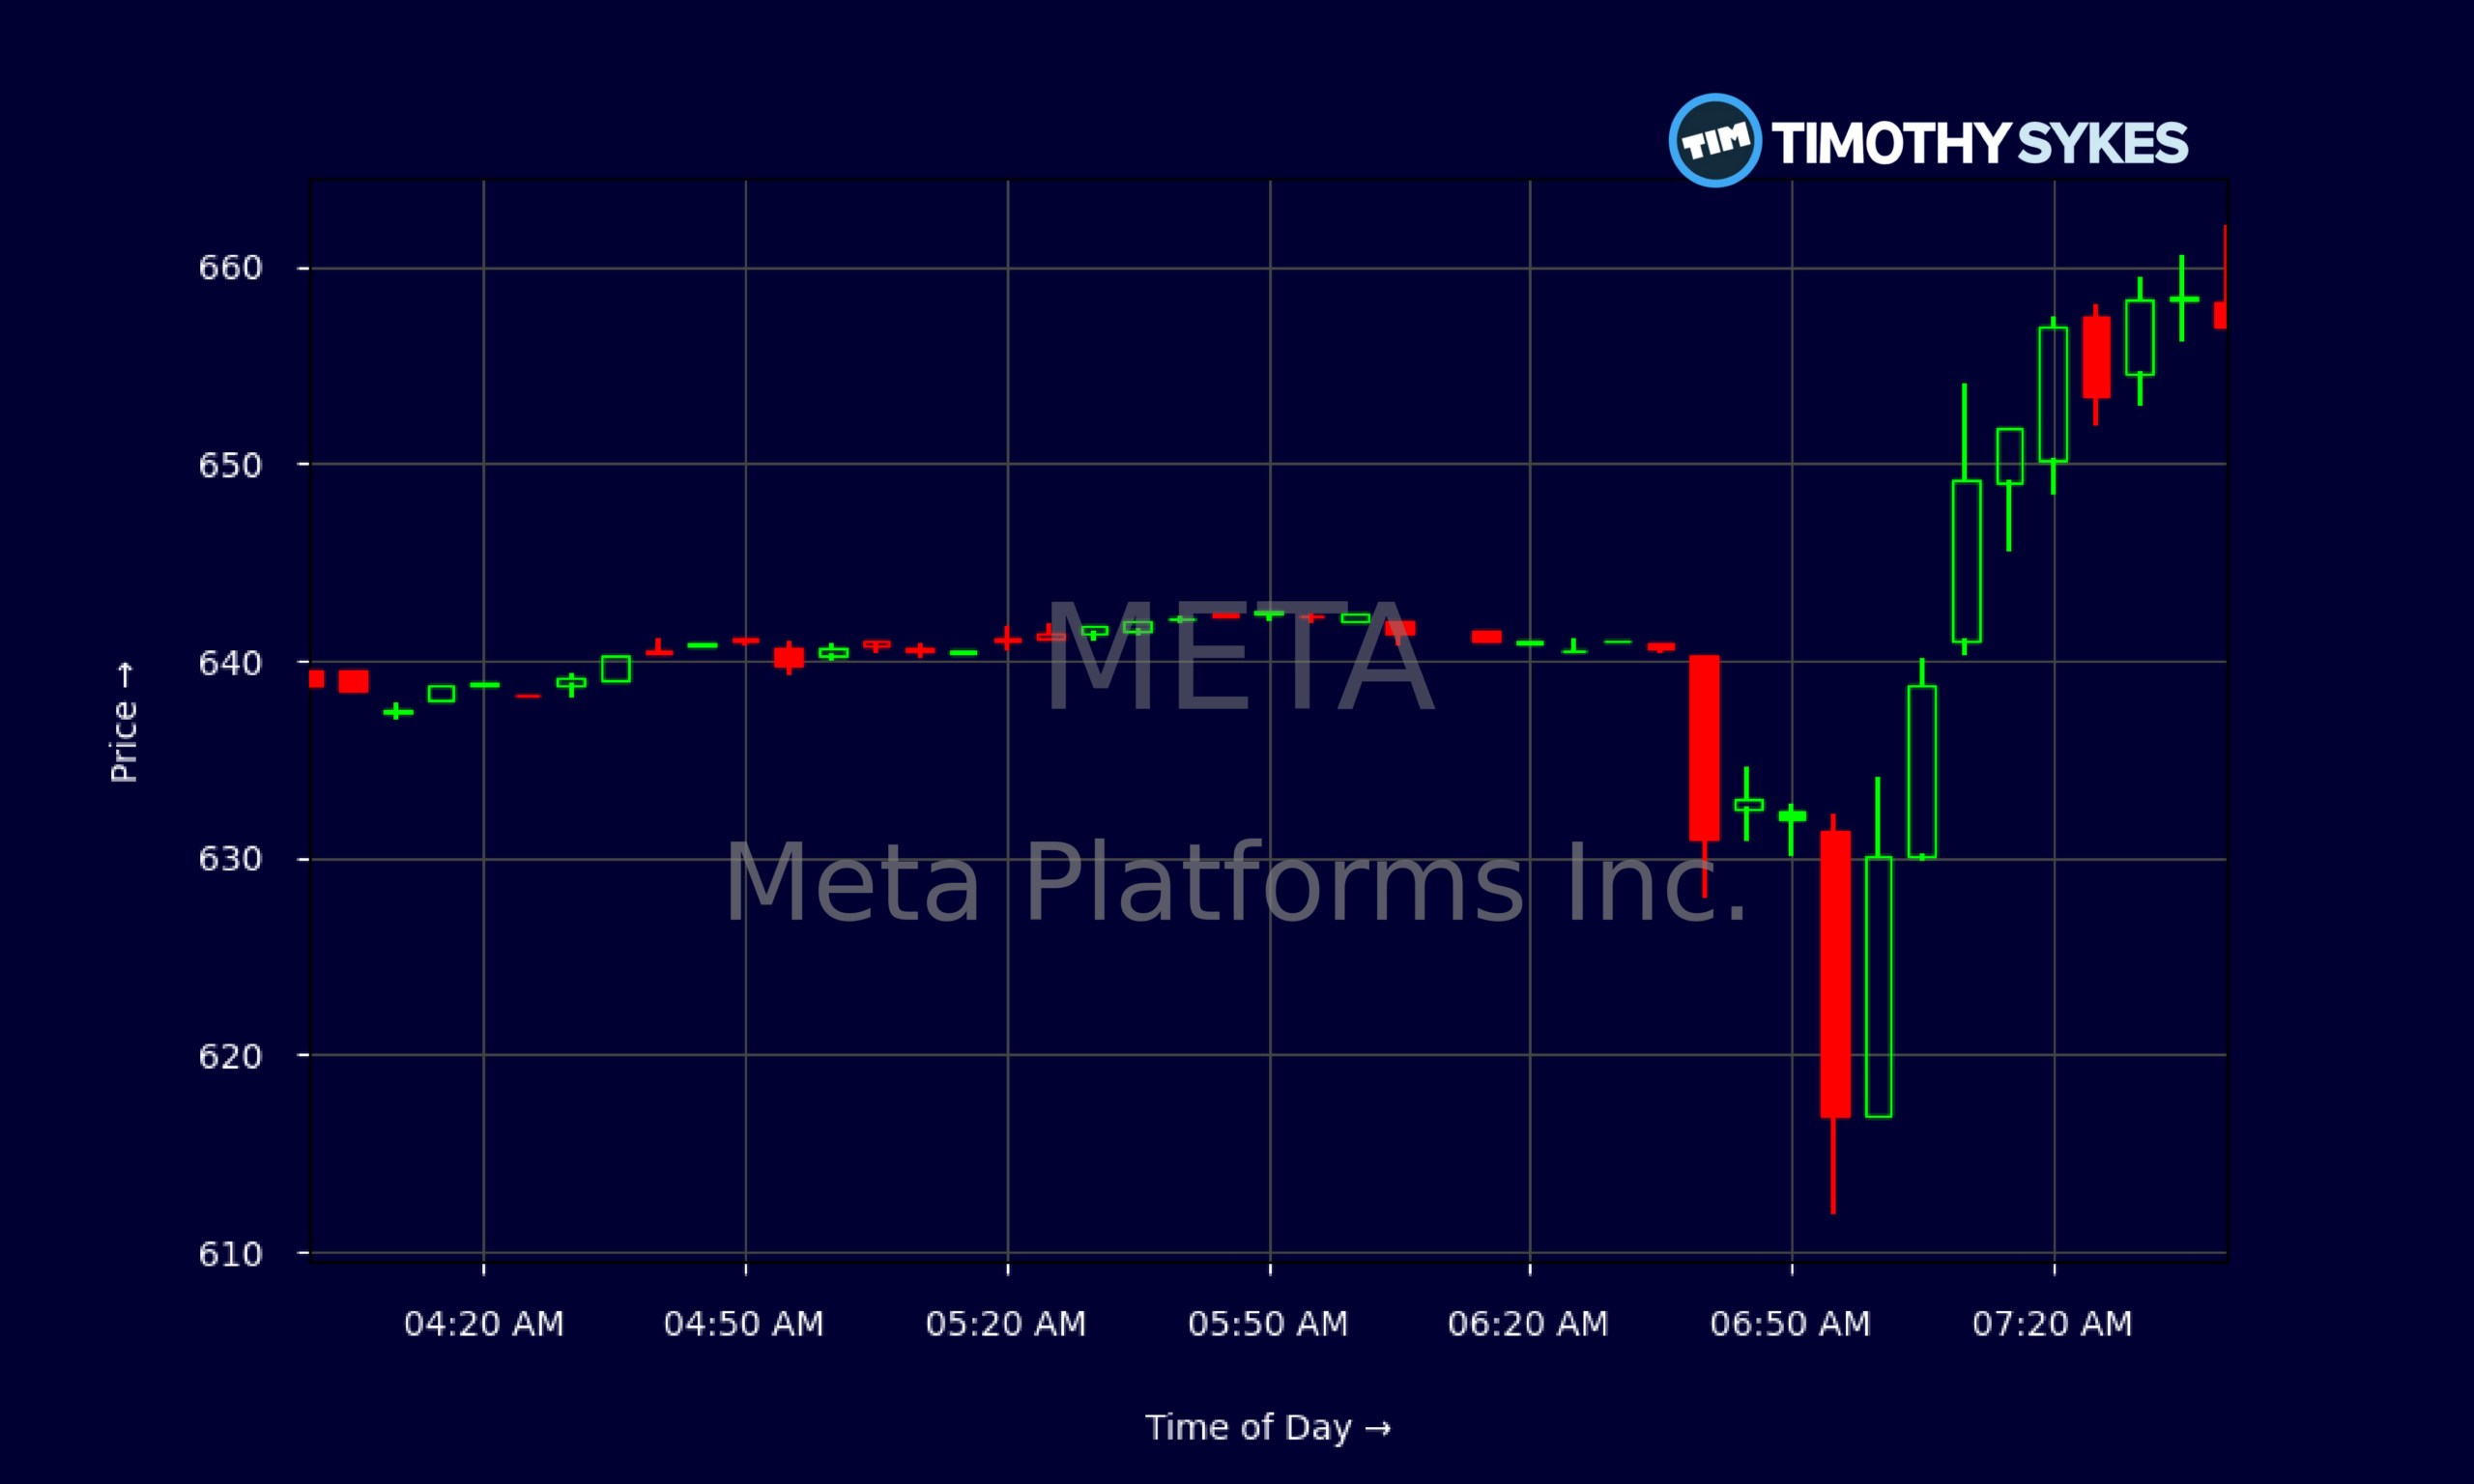
Live Update At 07:47:53 EDT: On Monday, October 26, 2026 Meta Platforms Inc. stock [NASDAQ: META] is trending up by 2.15%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
META’s recent numbers tell a story every active trader should study. Revenue over the last year sits near $201B, growing at roughly mid‑20% rates, while net margins close to 30% show the core ad machine is still a cash factory. An EBIT margin above 36% and EBITDA margin above 46% back up that view.
On the balance sheet, Meta Platforms Inc. carries moderate leverage. Total debt-to-equity around 0.43 and strong interest coverage north of 150x mean solvency risk is low, even with capex ramping. Current and quick ratios around 2 show META comfortably covering near-term obligations.
Valuation is no longer cheap. A P/E near 27 and price-to-sales over 8 signal that traders are already paying up for growth and AI optionality. The big outlier is price-to-free-cash near 262, reflecting how aggressive capital spending and a one-time $9.9B legal charge have crushed near-term free cash flow.
More Breaking News
On the tape, META has pulled back from recent highs above $760 to the low $640s, with a series of lower highs on the daily chart. Intraday, the stock showed heavy volatility, whipping between the low $610s and mid-$660s. For short-term traders, this mix of strong fundamentals, rich valuation, and elevated volatility sets the stage for sharp momentum swings around headlines and key technical levels.
Why Traders Are Locked In On META’s AI Story
META is in a rare spot where fundamentals, narrative, and sell-side backing are moving in the same bullish direction. Q3 2026 came in hot: 26% revenue growth and 265% EPS growth even while booking a $9.9B legal hit tied to U.S. state AG teen-mental-health litigation. Despite that drag, guidance still points to strong revenue growth into Q4 and 2027, a key backdrop for any trading thesis.
Under the hood, the ad engine is being rewired by AI. Meta Platforms Inc. reports 3.64B daily users across its apps and all-time-high engagement on Facebook and Instagram, driven by video. That engagement gives META a huge sandbox to deploy its AI agent, Muse, which management calls one of its most successful launches ever. The company is targeting more than 10x cost-efficiency gains for Muse within a year, opening a path to profitability at scale rather than just another costly science project.
Muse and the new frontier model Muse Wonder are already showing teeth. Pivotal Research notes the Muse assistant hit 2.8M installs in just 12 days, and says Muse Wonder performs at or near parity with leading frontier AI labs. That kind of technical credibility explains why Barclays, UBS, Citi, Rosenblatt, and others all lifted META price targets into the $880–$900+ range after Q3.
At the top end, Truist now sees META at $1,000, while Pivotal Research sits at $930 and $960 across two recent updates. Morgan Stanley, Goldman Sachs, Guggenheim, and DA Davidson cluster in the $800s, with the average Street target around the low $800s. For momentum traders, this dense “Buy” wall and a rising target distribution can act like a psychological floor on big dips—at least as long as the AI and ad metrics keep delivering.
The capital structure move matters too. META announced a new non-voting Class C share, effectively a 2-for-1 split in 2027, designed to fund large AI and infrastructure builds and deals without flooding the market with voting stock or diluting control. Pivotal Research argues that this eases near-term equity overhang fears, another tailwind for sentiment as traders look for catalysts into the next earnings cycle.
Conclusion
For active traders, META is now a classic “high-expectation, high-volatility” name. The core business is throwing off massive operating cash flow — over $32B in the latest quarter — even as free cash flow briefly turned negative under the weight of $33.9B in capex and that $9.9B legal charge. The market is clearly betting that this spending, especially around Muse and Muse Wonder, is laying track for higher-margin AI revenue rather than just bloating costs.
The risk side is straightforward. Valuation on META is no bargain, and any stumble in AI execution, user growth, or ad pricing can hit a stock already trading at premium multiples. Add ongoing legal and regulatory pressure, and you have plenty of headline risk to fuel gap-ups and gap-downs that reward only the most disciplined traders.
But the opportunity is just as clear. Record 3.64B daily users, surging video engagement, and a fast-scaling AI stack have convinced major firms — from Goldman Sachs and Morgan Stanley to Citi, UBS, Truist, and Barclays — to push META targets into the $800–$1,000 zone. The new Class C share, frontier models like Muse Wonder, and even collaboration around open-weight AI for Apple Macs all signal that Meta Platforms Inc. is positioning as a top-tier AI platform, not just a social ad play.
Tim Sykes loves to remind traders: “Patterns repeat because human nature doesn’t change — study the past charts, respect the risks, and focus on process over profits.” As millionaire penny stock trader and teacher Tim Sykes says, “It’s not about how much money you make; it’s about how much money you keep.” META’s chart, news flow, and numbers are offering that kind of teaching moment right now. Use this data for education and research, build your trading plan, and remember — no single ticker is worth blowing up your account.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply