Applied Digital Corp. stocks have been trading up by 9.45 percent following upbeat sentiment on its expanding AI infrastructure capabilities.
Key Takeaways Traders Are Watching
- Fiscal Q1 2027 from Applied Digital blew past expectations, with EPS of $0.01 versus a forecast loss and revenue triple Street models on AI data center and GPU-driven services.
- Long-term AI/HPC leases now represent about $36B in contracted revenue, potentially rising to roughly $86B with renewals, backed by $1.59B of secured notes on APLD’s balance sheet.
- Management guided Q3 revenue slightly above consensus and flagged gross margins above 70%, signaling confidence in Applied Digital’s underlying AI services model.
- A new deal for up to 1 GW of power in Finland opens Applied Digital’s first international AI Factory campus, targeted for 2028 with a capital-light structure.
- Wells Fargo and Morgan Stanley raised price targets on APLD, while Needham trimmed but kept a Buy, reflecting strong AI momentum but real funding and regulatory risks.
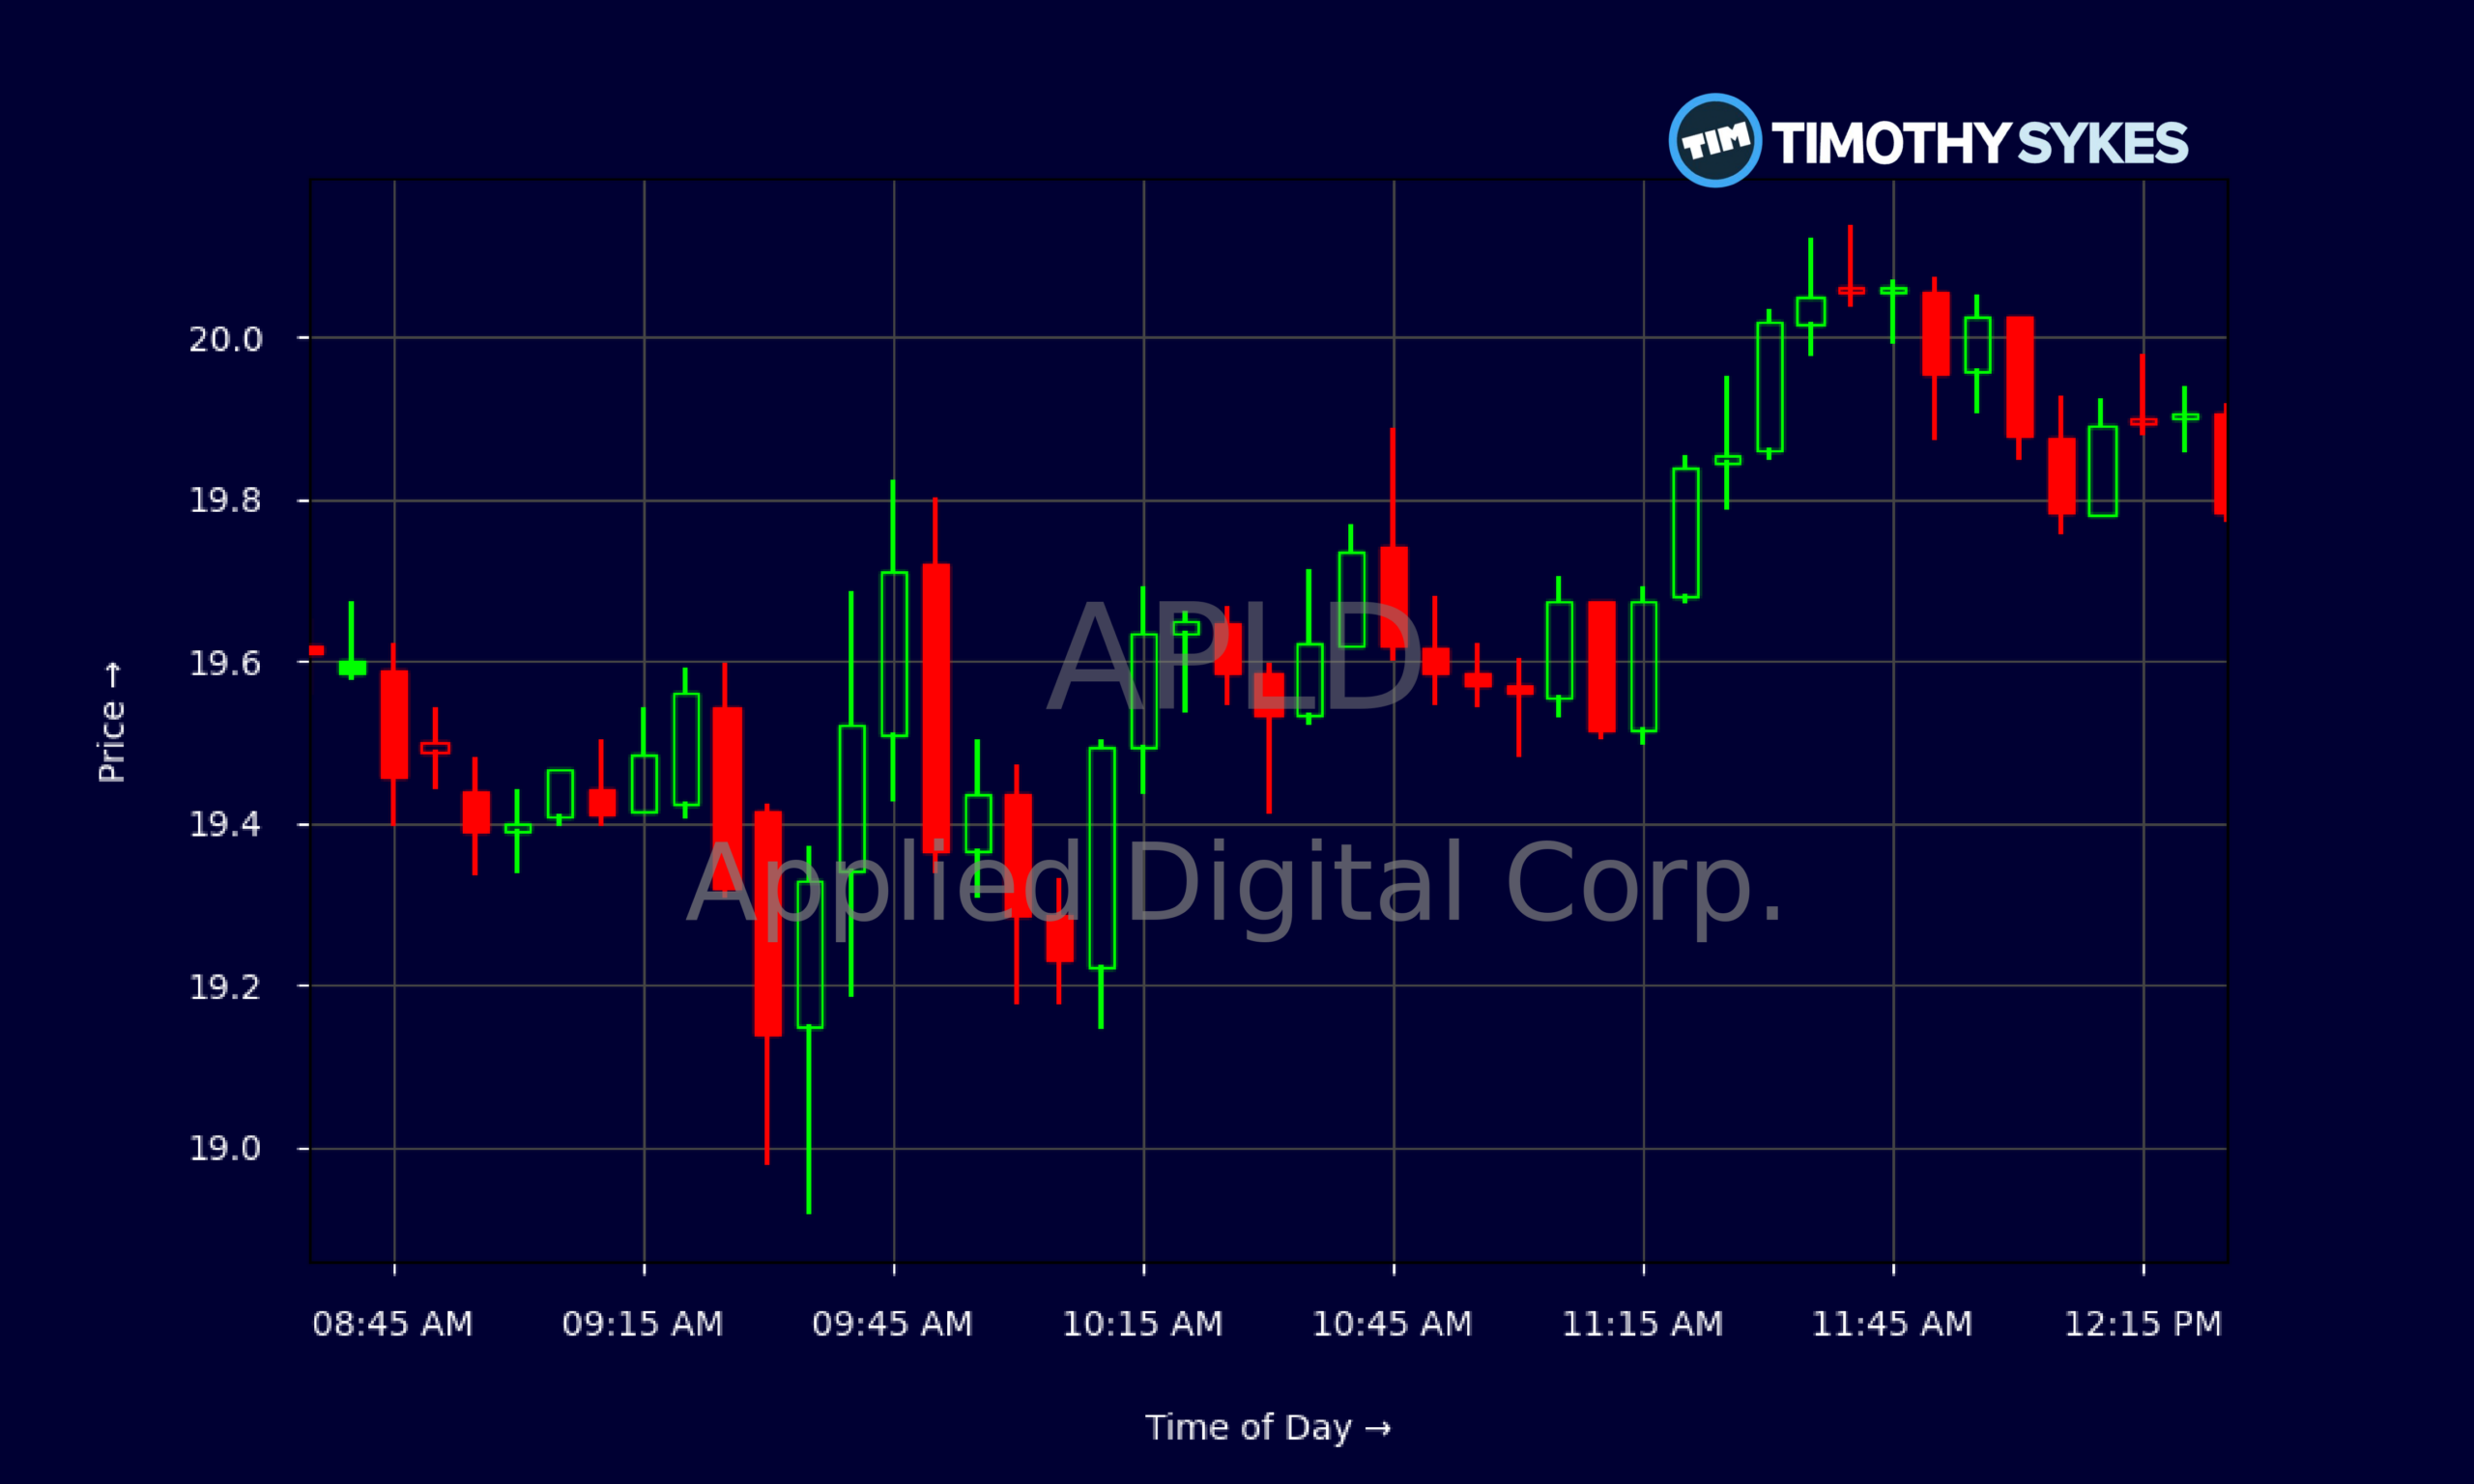
Live Update At 12:32:20 EDT: On Monday, October 19, 2026 Applied Digital Corp. stock [NASDAQ: APLD] is trending up by 9.45%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
APLD has been trading like a classic high-beta AI infrastructure story. The daily chart shows the stock sliding from the mid-$20s to the high teens over the past few weeks, with closes moving from around $27.06 down to $19.76. That’s a meaningful pullback after a strong prior run, and it sets up a classic battleground zone for active trading.
Intraday, Applied Digital has been tight but active. On the latest 5‑minute tape, APLD ranged roughly between $18.40 and $20.14, with repeated tests just under $20 and quick rejections above that level. That tells traders $20 is the near-term pivot where short-term momentum traders and bigger funds are clashing.
More Breaking News
Fundamentals explain why the stock remains in play. Applied Digital posted revenue of $341.9M for fiscal Q1 2027 versus only $80.9M a year earlier. Yet the company is still showing a GAAP net loss of $184.1M, reflecting heavy growth spending and financing costs. Returns on equity and assets remain sharply negative, and free cash flow is deeply in the red, but liquidity is strong with a current ratio of 5.4 and cash of about $2.95B. For traders, that combination screams “hyper-growth, high-risk story” where news flow and sentiment will keep dictating direction.
Why Traders Are Zooming In On APLD
The reason Applied Digital is front and center for momentum traders right now is simple: this is one of the purest listed plays on AI data center build‑out. APLD’s fiscal Q1 2027 numbers shocked the Street. Earnings per share came in at $0.01, versus a consensus call for a ($0.30) loss. Revenue printed at $341.9M, compared with estimates in the $116M–$125M range. That’s not a beat, that’s a reset.
The driver was a 225% year‑over‑year surge in services revenue tied to tenant fit‑out work and GPU hardware sales for its ChronoScale platform. In plain English, Applied Digital is not just leasing power and space; it is wiring up purpose‑built AI factories and supplying hardware to hyperscale customers hungry for compute. Traders love that narrative, but they also need to remember that some of those fit‑out revenues are one‑time in nature.
At the same time, the long‑term picture for APLD is massive. Management now pegs contracted revenue at roughly $36B over base lease terms, with potential to approach $86B if customers exercise renewals. That is backed by heavy leverage, including $1.59B in secured notes, so the company looks more like an emerging AI infrastructure landlord than a simple hosting shop.
Execution is showing up on the ground too. Applied Digital just brought the second phase of Building 2 at its Polaris Forge 1 AI Factory campus to Ready for Service, adding 75MW of IT load and completing that building’s 150MW. The campus now has 250MW online within a fully leased 400MW plan. For traders, that means capacity is not theoretical; it is switching on and already spoken for.
Layer in the Finland deal—access to up to 1 GW of power for APLD’s first international AI Factory campus, with initial power expected in 2028 and a capital‑disciplined structure—and you get a clear runway for more contracts. Analysts are taking note: Wells Fargo lifted its price target to $55 with an Overweight stance, citing strong execution on a 1.4 GW build‑out and future Meta‑linked lease financing. Morgan Stanley nudged its target to $41 with Equal Weight, acknowledging pipeline value but highlighting tougher credit conditions. Needham trimmed its target to $70, still at Buy, flagging one‑off revenue and rising regulatory and financing risks. In short, Applied Digital sits at the crossroads of huge AI upside and serious capital‑market sensitivity.
Conclusion
For active traders, APLD offers what they crave most: volatility backed by real numbers, not vague promises. Applied Digital’s fiscal Q1 2027 report showed revenue exploding to $341.9M and the adjusted loss tightening to just $0.01 per share, while guidance calls for Q3 revenue of $9.8M–$10M with gross margins north of 70%. That kind of margin profile, if it holds as the mix shifts away from one‑time fit‑out work, can support a powerful earnings story over time.
But the flip side is just as important to respect. Applied Digital is running a highly leveraged balance sheet to secure and build data center capacity, including the $1.59B of secured notes. Free cash flow remains sharply negative, and returns on equity and assets are deep in the red as the company races to scale. That makes APLD extremely sensitive to credit markets, interest rates, and any regulatory shifts around power and data centers.
The tape confirms this push‑pull. APLD has pulled back from the $20s into the high teens even as Wall Street raises or reaffirms constructive price targets, and insiders such as director Richard Nottenburg are selectively selling while still holding meaningful stakes. For traders studying Applied Digital, this is a classic Sykes‑style setup: a hot story, explosive numbers, and real risk. As Tim Sykes likes to remind his community, “It’s not about being right, it’s about managing risk so you can trade again tomorrow.” As millionaire penny stock trader and teacher Tim Sykes, says, “The goal is not to win every trade but to protect your capital and keep moving forward.”. This article is for educational and research purposes only and should never be taken as trading advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply